We value your privacy
We use cookies to improve your experience and analyze traffic. By continuing, you consent to our use of cookies under GDPR, CCPA and other applicable laws. Privacy Policy
Cookie preferences
Choose which categories of cookies you allow. Strictly necessary cookies are always on.
Strictly necessary
Required for core site functionality, security and your session. Always active.
Analytics
Help us understand how visitors use the site (e.g. Google Analytics) so we can improve it.
Marketing
Used to measure campaigns and show you relevant ads on other sites (e.g. LinkedIn, Google Ads).
Telehealth Technology Market Analysis size 2021 was recorded $64376 Million whereas by the end of 2026 it will reach $191234.34 Million. According to the author, by 2033 Telehealth Technology market size will become $877858. Telehealth Technology market will be growing at a CAGR of 24.325% during 2026 to 2033. Download a free sample with data verified by Supriya Yadav
Telehealth Technology Market Analysis from 2022 to 2034 Containing Market Size, Share along with its CAGR, Forecast and Trends
Top Countries — Revenue
Billion
Market Dynamics of Telehealth Technology Market Analysis
Growth Drivers
Chronic disease management demand:
Regulatory permanence:
Provider efficiency needs:
Restraints
Reimbursement disparities:
Tech literacy gaps:
Diagnostic limitations:
Trends
Hospital-at-home technology:
AI diagnostic augmentation:
Vertical-specific platforms:
Access the full forecast model.
Country-level data · Company profiles · Editable dataset · Analyst consultation included.
Telehealth Technology Market Analysis — Presence
Geographical Analysis
Click countries to explore
Loading map…
Regional and Country Analysis
Global Telehealth Technology Market Analysis 2026
Country-level values are locked in this preview.
Request a free sample
to unlock the full breakdown.
Region / Country
2021 (A)
2025 (A)
2033 (P)
CAGR
Global
$ 64.38 Billion
$ 153.8 Billion
$ 877.86 Billion
24.325%
North America
$ 25.75 Billion
$ 61.2 Billion
$ 337.36 Billion
23.786%
United States
$ 21.16 Billion
$ 48.04 Billion
$ 260.85 Billion
23.552%
Canada
$ 1.92 Billion
$ 4.61 Billion
$ 29.55 Billion
26.149%
Mexico
$ 2.67 Billion
$ 8.55 Billion
$ 46.96 Billion
23.73%
Europe
$ 18.61 Billion
$ 44.13 Billion
$ 245.19 Billion
23.908%
United Kingdom
$ 1.97 Billion
$ 4.21 Billion
$ 21.99 Billion
22.974%
France
$ 2.86 Billion
$ 6.8 Billion
$ 40.36 Billion
24.934%
Germany
$ 3.29 Billion
$ 7.78 Billion
$ 40.65 Billion
22.961%
Italy
$ 1.46 Billion
$ 3.49 Billion
$ 21.97 Billion
25.854%
Russia
$ 0.44 Billion
$ 0.97 Billion
$ 4.81 Billion
22.202%
Spain
$ 1.25 Billion
$ 2.8 Billion
$ 16.35 Billion
24.697%
Sweden
$ 1.11 Billion
$ 2.46 Billion
$ 11.7 Billion
21.53%
Denmark
$ 0.58 Billion
$ 1.33 Billion
$ 6.96 Billion
23.011%
Switzerland
$ 0.71 Billion
$ 1.51 Billion
$ 7.41 Billion
21.952%
Luxembourg
$ 0.26 Billion
$ 0.59 Billion
$ 2.96 Billion
22.334%
Rest of Europe
$ 4.68 Billion
$ 12.2 Billion
$ 70.03 Billion
24.417%
Asia Pacific
$ 12.17 Billion
$ 29.39 Billion
$ 184.09 Billion
25.777%
China
$ 3.82 Billion
$ 8.99 Billion
$ 56.15 Billion
25.725%
Japan
$ 2.23 Billion
$ 5.14 Billion
$ 29.82 Billion
24.569%
South Korea
$ 1.16 Billion
$ 2.91 Billion
$ 19.15 Billion
26.554%
India
$ 1.88 Billion
$ 4.51 Billion
$ 29.91 Billion
26.676%
Australia
$ 0.31 Billion
$ 0.68 Billion
$ 3.7 Billion
23.542%
Singapore
$ 0.2 Billion
$ 0.51 Billion
$ 4.07 Billion
29.5%
Taiwan
$ 0.27 Billion
$ 0.63 Billion
$ 3.33 Billion
23.099%
South East Asia
$ 1.29 Billion
$ 3.16 Billion
$ 21.25 Billion
26.904%
Rest of APAC
$ 1.01 Billion
$ 2.85 Billion
$ 16.71 Billion
24.766%
South America
$ 4.38 Billion
$ 10.78 Billion
$ 66.19 Billion
25.463%
Brazil
$ 1.7 Billion
$ 4.21 Billion
$ 25.15 Billion
25.036%
Argentina
$ 0.63 Billion
$ 1.52 Billion
$ 9 Billion
24.953%
Colombia
$ 0.39 Billion
$ 1 Billion
$ 6.05 Billion
25.292%
Peru
$ 0.23 Billion
$ 0.52 Billion
$ 2.42 Billion
21.167%
Chile
$ 0.14 Billion
$ 0.32 Billion
$ 1.67 Billion
23.174%
Rest of South America
$ 1.29 Billion
$ 3.23 Billion
$ 21.9 Billion
27.055%
Middle East
$ 2.51 Billion
$ 5.68 Billion
$ 29.5 Billion
22.878%
Saudi Arabia
$ 0.93 Billion
$ 2.13 Billion
$ 11.32 Billion
23.181%
Turkey
$ 0.29 Billion
$ 0.62 Billion
$ 3 Billion
21.791%
UAE
$ 0.29 Billion
$ 0.65 Billion
$ 3.09 Billion
21.459%
Egypt
$ 0.18 Billion
$ 0.42 Billion
$ 3.3 Billion
29.389%
Qatar
$ 0.19 Billion
$ 0.41 Billion
$ 2.06 Billion
22.232%
Rest of Middle East
$ 0.63 Billion
$ 1.44 Billion
$ 6.74 Billion
21.316%
Africa
$ 0.97 Billion
$ 2.63 Billion
$ 15.54 Billion
24.862%
East Africa
xxxx
xxxx
xxxx
xxxx
West Africa
xxxx
xxxx
xxxx
xxxx
North Africa
xxxx
xxxx
xxxx
xxxx
South Africa
$ 0.34 Billion
$ 0.91 Billion
$ 5.14 Billion
24.096%
The global Telehealth Technology market is undergoing a profound transformation, evolving from a supplementary service to an integral component of the healthcare ecosystem. Driven by the convergence of technology and healthcare, the market is expanding rapidly, offering solutions that enhance patient access, improve care quality, and reduce costs. This dynamic growth is supported by increasing smartphone penetration, advancements in digital health infrastructure, and a growing acceptance of virtual consultations by both patients and providers. The market's evolution reflects a broader trend towards patient-centered, accessible, and efficient healthcare delivery models on a global scale.
Global Telehealth Technology Market Drivers
Rising Prevalence of Chronic Diseases and Aging Population: The increasing global burden of chronic conditions like diabetes, cardiovascular diseases, and hypertension necessitates continuous monitoring and management. Telehealth technologies, particularly remote patient monitoring, provide an effective and efficient way to manage these conditions, driving market growth as the world's population ages.
Technological Advancements and Digital Connectivity: The proliferation of high-speed internet, widespread smartphone adoption, and advancements in wearable devices and AI have created a robust technological foundation for telehealth services. These innovations enhance the quality of virtual care, making it more reliable, accessible, and user-friendly for a broader population.
Increased Focus on Healthcare Accessibility and Cost-Effectiveness: Telehealth bridges the gap in healthcare access for rural and underserved populations, reduces travel time and costs for patients, and optimizes resource allocation for healthcare providers. Favorable government policies and expanding reimbursement coverage, accelerated by the recent global health crisis, have further solidified telehealth's role as a cost-effective solution.
Global Telehealth Technology Market Trends
Integration of Artificial Intelligence (AI) and Big Data Analytics: AI algorithms are being increasingly integrated into telehealth platforms for predictive diagnostics, personalized treatment plans, and chatbot-assisted patient triage. The analysis of big data from telehealth interactions is providing valuable insights into population health trends and care effectiveness, paving the way for more proactive healthcare.
Expansion of Remote Patient Monitoring (RPM): Beyond virtual consultations, the market is seeing a significant trend towards the adoption of RPM devices for real-time monitoring of vital signs and chronic conditions. This allows for early intervention, reduces hospital readmissions, and empowers patients to take a more active role in managing their health from home.
Diversification into Specialized Care and Mental Health: Telehealth is expanding beyond urgent care and general consultations into specialized fields like tele-dermatology, tele-radiology, and tele-cardiology. There is a particularly strong upward trend in tele-mental health services, which offer a discreet, accessible, and effective way for individuals to receive psychological support and therapy.
Global Telehealth Technology Market Restraints
Data Privacy and Cybersecurity Risks: The transmission and storage of sensitive patient health information (PHI) over digital networks expose telehealth platforms to significant cybersecurity threats and data breaches. Ensuring robust security measures and compliance with regulations like HIPAA is a major concern that can hinder adoption if not addressed adequately.
Regulatory and Reimbursement Hurdles: The legal and regulatory landscape for telehealth is complex and varies significantly across different regions and countries. Issues related to clinician licensing across state or national borders, inconsistent reimbursement policies from insurers, and evolving legal frameworks can create significant barriers to market expansion.
The Digital Divide and Technology Literacy: Disparities in access to reliable internet and digital devices, particularly among the elderly and in lower-income or rural communities, create a "digital divide." A lack of technological literacy or comfort with digital platforms among certain patient demographics can limit the reach and effectiveness of telehealth solutions.
Market Size: $25,750 Million (2021) -> $61,197 Million (2025) -> $337,361 Million (2033)
CAGR (2021-2033): 23.786%
Holding approximately 39.79% of the global market in 2025, North America is the largest telehealth market, led by the United States. The U.S. alone is expected to command 31.23% of the global market in 2025, with significant contributions from Canada (2.99%) and Mexico (5.56%). This dominance is fueled by advanced healthcare infrastructure, high digital literacy, and favorable reimbursement policies established post-pandemic.
Key Drivers
Well-established healthcare IT infrastructure and high internet penetration.
Favorable government initiatives and strong reimbursement frameworks, particularly in the U.S.
High prevalence of chronic diseases and a strong push for value-based care.
Key Trends
Rapid adoption of AI and machine learning for predictive analytics in diagnostics.
Integration of telehealth with employer-based health and wellness programs.
Strong focus on tele-mental health and specialized virtual care services.
Key Restraints
Complex state-by-state licensing regulations for healthcare providers in the U.S.
Ongoing concerns about data security and interoperability between different EHR systems.
Disparities in access and digital literacy in rural and low-income communities.
Technology Focus
The region's technology focus is on advanced, integrated platforms featuring high-definition video consultations, sophisticated remote patient monitoring (RPM) devices, AI-driven diagnostics, and seamless EMR/EHR integration.
Market Size: $18,605 Million (2021) -> $44,125 Million (2025) -> $245,186 Million (2033)
CAGR (2021-2033): 23.908%
Europe is the second-largest market, projected to account for about 28.69% of the global telehealth market by 2025. The market is fragmented but robust, with key countries like Germany (5.06% of global market share), France (4.42%), and the United Kingdom (2.73%) leading the way. Growth is driven by government-led digital health initiatives and the need to support aging populations.
Key Drivers
Strong government support and public healthcare funding for digital health initiatives (e.g., Germany's Digital Healthcare Act).
An aging population with a high incidence of chronic diseases requiring continuous care.
High-quality digital infrastructure across most of the continent.
Key Trends
Development of cross-border telehealth services within the EU.
Emphasis on data privacy and security, adhering to strict GDPR regulations.
Growth in prescription renewal and primary care consultation platforms.
Key Restraints
Fragmented regulatory and reimbursement systems across different countries.
Linguistic and cultural diversity requiring highly localized platform solutions.
Initial resistance to change from traditional healthcare systems and some patient groups.
Technology Focus
Technology focus is on GDPR-compliant, secure platforms with multi-language support. There is a strong emphasis on interoperability with national e-health systems and providing evidence-based digital therapeutics (DTx).
Market Size: $12,167 Million (2021) -> $29,391 Million (2025) -> $184,087 Million (2033)
CAGR (2021-2033): 25.777%
As the fastest-growing region, APAC is set to hold 19.11% of the global market by 2025. This dynamic growth is powered by countries like China (5.85% of global market), Japan (3.34%), and India (2.93%). The region's vast population, increasing smartphone penetration, and government push to bridge urban-rural healthcare gaps are key drivers.
Key Drivers
Massive patient population and significant gaps in healthcare access in rural areas.
Rapidly growing internet penetration and mobile-first consumer behavior.
Government initiatives promoting digital health to manage population health and rising healthcare costs.
Key Trends
The proliferation of "super-apps" that integrate telehealth services with e-commerce and other digital services.
Strong demand for low-cost, mobile-based telehealth solutions.
Increasing foreign investment and startup activity in the digital health sector.
Key Restraints
Highly varied and developing regulatory frameworks across the region.
Significant digital divide and infrastructure limitations in many rural parts of Southeast Asia and India.
Concerns over data localization laws and patient data privacy.
Technology Focus
The focus is on scalable, mobile-first platforms and lightweight applications that function well on lower-bandwidth networks. Integration with popular messaging apps and local payment gateways is also a key technological trend.
Market Size: $4,378 Million (2021) -> $10,781 Million (2025) -> $66,190 Million (2033)
CAGR (2021-2033): 25.463%
South America's telehealth market is rapidly emerging, expected to constitute 7.01% of the global market by 2025. Brazil is the regional powerhouse, accounting for 2.74% of the global market alone. The need to provide healthcare services to remote and underserved populations across the continent's vast geography is a primary growth driver.
Key Drivers
Urgent need to improve healthcare access for large populations in remote and rural areas.
Growing middle class with increasing disposable income and demand for better healthcare.
Governmental and private sector initiatives to modernize the healthcare system.
Key Trends
Public-private partnerships to fund and deploy telehealth infrastructure.
Use of telehealth for managing infectious diseases and public health surveillance.
Growth in mobile health (mHealth) applications for primary care and wellness.
Key Restraints
Economic instability and currency fluctuations impacting investment.
Uneven digital infrastructure and significant disparities in internet access.
Developing regulatory frameworks and low levels of reimbursement for virtual care.
Technology Focus
Technology efforts are centered on cost-effective, mobile-based solutions that can operate in low-bandwidth environments. There is also a focus on platforms for public health management and connecting specialists in urban centers with general practitioners in remote locations.
Market Size: $2,511 Million (2021) -> $5,675 Million (2025) -> $29,496 Million (2033)
CAGR (2021-2033): 22.878%
The Middle East telehealth market, representing 3.69% of the global share in 2025, is characterized by strong government investment in digital transformation. Wealthy Gulf states like Saudi Arabia (1.39% of global share) and the UAE (0.42%) are leading adoption, aiming to create world-class healthcare systems. Egypt also shows remarkable growth potential with a very high CAGR.
Key Drivers
Strong government vision and significant financial investment in healthcare technology as part of economic diversification plans.
High smartphone penetration and a digitally savvy population.
Demand for high-quality, convenient healthcare services from both locals and a large expatriate population.
Key Trends
Development of luxury or "concierge" telehealth services.
Integration of AI and robotics within state-of-the-art hospitals and clinics.
Partnerships with leading international healthcare providers to offer virtual specialist consultations.
Key Restraints
Strict data localization laws requiring patient data to be stored within the country.
Cultural preferences for in-person consultations for certain medical issues.
Regulatory frameworks that are still catching up with the pace of technological innovation.
Technology Focus
Technology focus is on high-end, premium platforms that offer a seamless user experience. There is strong interest in AI for chronic disease management, high-quality video consultation tools, and integration with national health data platforms.
Market Size: $966 Million (2021) -> $2,630 Million (2025) -> $15,538 Million (2033)
CAGR (2021-2033): 24.862%
Though starting from a smaller base, Africa's telehealth market shows strong growth potential, projected to capture 1.71% of the global market by 2025. Key markets include South Africa (0.59% of global share) and Nigeria (0.20%). Telehealth is seen as a transformative tool to leapfrog traditional healthcare infrastructure challenges and connect the continent's vast, underserved population to medical expertise.
Key Drivers
Severe shortage of healthcare professionals and infrastructure, making remote solutions critical.
High mobile phone penetration, providing a ready-made platform for mHealth services.
Support from NGOs and international health organizations to deploy digital health projects.
Key Trends
Use of basic SMS and USSD-based services for health information dissemination in low-connectivity areas.
Drone technology for delivering medical supplies in conjunction with telehealth consultations.
Focus on maternal health, infectious diseases (e.g., HIV, TB), and primary care triage.
Key Restraints
Extreme limitations in internet connectivity and reliable electricity in many regions.
Very low digital literacy rates and affordability challenges for many potential users.
Lack of comprehensive regulatory frameworks and government funding.
Technology Focus
The technology must be extremely lightweight, robust, and optimized for mobile devices and poor network conditions. Focus is on SMS/USSD platforms, offline-capable applications, and simple video/voice call functionalities.
A = Actual · E = Estimated · P = Projected · 🔒 Locked values require full access. Click headers to sort.
Type breakdown · Illustrative 2025 shares shown free · Full-period forecast in paid report.
Software Telehealth Technology Market Analysis
XX
Software Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Hardware Telehealth Technology Market Analysis
XX
Hardware Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Service Telehealth Technology Market Analysis
XX
Service Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Market size by (Illustrative, 2025)
Share distribution (2025)
Disclaimer: The charts and graphs are for illustrative purposes only and do not represent actual market values. To access accurate quantitative data, please request a paid report or request free sample.
To learn more about market share and segmentation, request the free sample pages.
Competitor Analysis
The pharmaceutical and healthcare industry is highly competitive, with players expanding through product launches, M&A, partnerships, and regulatory approvals. The Telehealth Technology Market Analysis market report covers financials, market share, SWOTs, and responses to Tariffs, while providing global, regional, and country-level forecasts supported by value chain, patent analysis, and a competitive matrix serving as a key resource for stakeholders and investors.
Click any bar or cell to request the full company profile
Top Companies (In no particular order)
2022 (A)
2023 (A)
2024 (A)
2025 (A)
Medtronic
•••
•••
•••
•••
Siemens Healthineers
•••
•••
•••
•••
Philips Healthcare
•••
•••
•••
•••
Teladoc Health
•••
•••
•••
•••
Aerotel Medical Systems
•••
•••
•••
•••
AMD Global Telemedicine
•••
•••
•••
•••
InTouch Technologies
•••
•••
•••
•••
Vidyo
•••
•••
•••
•••
Resideo Technologies
•••
•••
•••
•••
Cerner Corporation
•••
•••
•••
•••
We Provide Regional Breakdown of this Companies and Company specific to any Country, Region, Product/ service as well. We cover market share analysis for publicly listed companies as well as privately held companies, subject to data availability.
The global Telehealth Technology market is experiencing an unprecedented surge, poised for exponential growth in the coming decade. Transitioning from a niche service to a mainstream healthcare delivery model, the market is projected to expand dramatically from $64,376 million in 2021 to $877,858 million by 2033. This remarkable growth, driven by a compound annual growth rate (CAGR) of 24.325%, is fueled by technological advancements, increased patient demand for convenience, and a global push to improve healthcare accessibility. The COVID-19 pandemic acted as a significant catalyst, accelerating adoption and breaking down long-standing regulatory and behavioral barriers. While North America currently holds the largest market share, the Asia-Pacific region is emerging as the fastest-growing market, indicating a global shift in healthcare dynamics. The integration of AI, IoT, and remote patient monitoring tools is further revolutionizing the landscape, offering more personalized and proactive care. However, addressing challenges related to data security, digital literacy, and cross-border regulations will be crucial for sustaining this momentum and realizing the full potential of telehealth.
Key strategic insights from our comprehensive analysis reveal:
The market is on a trajectory of explosive growth, with a global CAGR of 24.325%, indicating a fundamental shift in how healthcare services are delivered and consumed worldwide.
North America maintains its lead in market size, but the Asia-Pacific region, with a CAGR of 25.777%, represents the most significant growth opportunity, driven by burgeoning digital infrastructure and healthcare needs in countries like India and China.
The future of telehealth will be shaped by the integration of advanced technologies like AI for diagnostics, remote patient monitoring (RPM) for chronic disease management, and a focus on creating secure, user-friendly platforms to build patient and provider trust.
Strategic Recommendations for Manufacturers
To capitalize on the burgeoning Telehealth Technology market, manufacturers must prioritize a multi-faceted strategy. Firstly, invest heavily in creating user-centric designs with intuitive interfaces for both patients and healthcare providers to ensure high adoption and engagement rates. Secondly, place paramount importance on cybersecurity by integrating end-to-end encryption and complying with international data protection regulations like GDPR and HIPAA to build trust. Thirdly, develop modular and interoperable platforms that can seamlessly integrate with existing electronic health record (EHR) systems and third-party applications, facilitating a connected healthcare ecosystem. Finally, pursue a strategy of localization by adapting platforms to meet regional regulatory requirements, language needs, and specific healthcare challenges, particularly when expanding into high-growth markets like APAC and South America.
The pharmaceutical and healthcare industry is growing rapidly, driven by aging populations, chronic disease prevalence, and rising healthcare spending. Innovations in precision medicine, gene therapy, and digital health are improving outcomes, though challenges include high R&D costs, strict regulations, and pricing pressures. Growth opportunities lie in emerging markets with expanding healthcare infrastructure, while key trends such as AI-driven personalized medicine, telehealth, and sustainable pharma solutions are reshaping the industry.
Analyst Conclusion
As per Cognitive's Research Analyst, Telehealth Technology are an integral component of the evolving healthcare delivery model, leveraging digital communication and information technologies. They play an essential role in enhancing patient access, improving care quality, and reducing costs by providing remote medical consultations, monitoring, and health management for chronic conditions and diverse medical fields.
Looking at the Historical Growth The global market expanded from $64,376 million in 2021 to an estimated $191234.34 million in 2026 due to increased patient demand for convenience and a global push to improve healthcare accessibility, significantly accelerated by the COVID-19 pandemic which catalyzed adoption. Regionally, North America grew from $25,750 million in 2021 to $75752.28 million in 2026, while Europe progressed from $18,605 million to $54674.96 million over the same period.
Currently in 2026, North America holds a commanding 39.61% of the global market, driven by advanced healthcare infrastructure, high digital literacy, and favorable reimbursement policies established post-pandemic. The remote patient monitoring applications segment remains the primary consumer of Telehealth Technology. Additionally Asia Pacific is set to be the fastest-growing region, exhibiting the highest CAGR of 25.777%, fueled by a massive patient population, rapid growth in internet penetration, and government initiatives to bridge urban-rural healthcare gaps.
The market is witnessing a definitive shift towards the integration of Artificial Intelligence (AI) and Remote Patient Monitoring (RPM) tools, driven by predictive diagnostics, personalized treatment plans, and real-time monitoring of chronic conditions. Ongoing innovation in platform development is also leading, focusing on ensuring seamless integration with existing electronic health records and prioritizing robust data security.
In the future, The global Telehealth Technology market will reach to $877,858 million by 2033, expanding at a compound annual growth rate of 24.325% from 2021, primarily driven by the rising prevalence of chronic diseases, a rapidly aging population, and continuous technological advancements in digital connectivity. Ongoing innovation in AI and wearable devices and the strong trend towards patient-centered, accessible, and efficient healthcare delivery will also contribute significantly.
Supriya is a Team Lead at Cognitive Market Research & Consulting, leading research initiatives and strategic intelligence projects across the Healthcare, Pharmaceuticals, and Medical Devices & Consumables sectors. With more than two years of experience in market research and data analysis, she plays a key role in helping organizations navigate complex healthcare ecosystems, identify emerging opportunities, and make informed business decisions through data-driven insights and market intelligence.
Combining expertise in both primary and secondary research methodologies with a strong academic foundation in Marketing and Finance, Supriya oversees the execution of market assessments, competitive intelligence studies, forecasting models, stakeholder interviews, trend analysis, and custom consulting engagements. She collaborates with healthcare providers, pharmaceutical manufacturers, medical device companies, industry experts, and other key stakeholders to gather firsthand market perspectives while validating findings through extensive research. Her ability to interpret clinical, commercial, and market data enables clients to better understand industry developments, regulatory influences, innovation trends, and competitive dynamics.
In her leadership role, she manages end-to-end research projects and guides cross-functional teams in delivering high-quality market reports, consulting solutions, and strategic studies. Her expertise in market estimation, forecasting, and analytical modeling helps organizations evaluate market potential, assess growth opportunities, strengthen competitive positioning, and support strategic planning initiatives. By transforming complex healthcare and life sciences data into actionable business intelligence, she enables clients to make confident decisions in rapidly evolving market environments.
Driven by a passion for healthcare innovation and continuous professional development, Supriya remains committed to staying ahead of industry trends, technological advancements, and changing market conditions. Her leadership, analytical mindset, and dedication to research excellence help organizations mitigate risks, capitalize on emerging opportunities, and achieve sustainable growth across the global healthcare and life sciences landscape.
Telehealth Technology Market Analysis market size and growth rate is provided in the report covering 2021-2025 historical and 2025-2033 forecast data.
Major factors including drivers, restraints, opportunities and challenges are analyzed with detailed insights.
Top manufacturers Medtronic, Siemens Healthineers, Philips Healthcare, Teladoc Health, Aerotel Medical Systems, AMD Global Telemedicine, InTouch Technologies, Vidyo, Resideo Technologies, Cerner Corporation and others are profiled in the report.
Segments include Type, Application and additional sub-segments.
Regional analysis covers all major markets. The report identifies the dominant region and provides country-level data.
Sample pages can be obtained on demand from the website. 24/7 chat support and direct call services are available.
★ Reviews
Rate this report
Telehealth Technology Market Analysis — Table of Contents
Disclaimer:
This is just a redacted sample pages of the actual deliverable report and only for representative purposes
Charts/Graphs/Numbers/data are only for Representative purposes and do not depict actual statistics.
The table of Contents differs according to the user License selection. Current Displayed TOC is for the Corporate User License Report Edition. TOC Customization options: Add or Remove section/s Or chapter/s from the report.
Specific Tables, Graphs, Sections, and Chapters can be ordered at a discounted price.
If applicable; On Request Volume Data will also be provided (at an Additional Cost).
Report Scope
Type
Software, Hardware, Service
Application
Hospitals, Clinics, Diagnostic Centers, Others
List of Competitors
Medtronic, Siemens Healthineers, Philips Healthcare, Teladoc Health, Aerotel Medical Systems, AMD Global Telemedicine, InTouch Technologies, Vidyo, Resideo Technologies, Cerner Corporation
Chapter 1. Competitor Analysis (Subject to Data Availability (Private Players))
1.1 Top Competitors Analysis
1.1.1 Global Telehealth Technology Market Analysis by Key Players
1.1.2 Segment Market Analysis by Key Players
1.1.3 Top Players Ranking 2024
1.1.4 New Product Launch Analysis
1.1.5 Industry Mergers and Acquisition Analysis
1.2 Company Profile (Data Subject to Availability) Sample Format
1.2.1 Medtronic
1.2.1.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.1.2 Business Overview
1.2.1.3 Financials (Subject to data availability)
1.2.1.4 R&D Investment (Subject to data availability)
1.2.1.5 Product Types Specification
1.2.1.6 Business Strategy
1.2.1.7 Recent Developments
1.2.1.8 Management Change
1.2.1.9 S.W.O.T Analysis
1.2.2 Siemens Healthineers
1.2.2.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.2.2 Business Overview
1.2.2.3 Financials (Subject to data availability)
1.2.2.4 R&D Investment (Subject to data availability)
1.2.2.5 Product Types Specification
1.2.2.6 Business Strategy
1.2.2.7 Recent Developments
1.2.2.8 Management Change
1.2.2.9 S.W.O.T Analysis
1.2.3 Philips Healthcare
1.2.3.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.3.2 Business Overview
1.2.3.3 Financials (Subject to data availability)
1.2.3.4 R&D Investment (Subject to data availability)
1.2.3.5 Product Types Specification
1.2.3.6 Business Strategy
1.2.3.7 Recent Developments
1.2.3.8 Management Change
1.2.3.9 S.W.O.T Analysis
1.2.4 Teladoc Health
1.2.4.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.4.2 Business Overview
1.2.4.3 Financials (Subject to data availability)
1.2.4.4 R&D Investment (Subject to data availability)
1.2.4.5 Product Types Specification
1.2.4.6 Business Strategy
1.2.4.7 Recent Developments
1.2.4.8 Management Change
1.2.4.9 S.W.O.T Analysis
1.2.5 Aerotel Medical Systems
1.2.5.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.5.2 Business Overview
1.2.5.3 Financials (Subject to data availability)
1.2.5.4 R&D Investment (Subject to data availability)
1.2.5.5 Product Types Specification
1.2.5.6 Business Strategy
1.2.5.7 Recent Developments
1.2.5.8 Management Change
1.2.5.9 S.W.O.T Analysis
1.2.6 AMD Global Telemedicine
1.2.6.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.6.2 Business Overview
1.2.6.3 Financials (Subject to data availability)
1.2.6.4 R&D Investment (Subject to data availability)
1.2.6.5 Product Types Specification
1.2.6.6 Business Strategy
1.2.6.7 Recent Developments
1.2.6.8 Management Change
1.2.6.9 S.W.O.T Analysis
1.2.7 InTouch Technologies
1.2.7.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.7.2 Business Overview
1.2.7.3 Financials (Subject to data availability)
1.2.7.4 R&D Investment (Subject to data availability)
1.2.7.5 Product Types Specification
1.2.7.6 Business Strategy
1.2.7.7 Recent Developments
1.2.7.8 Management Change
1.2.7.9 S.W.O.T Analysis
1.2.8 Vidyo
1.2.8.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.8.2 Business Overview
1.2.8.3 Financials (Subject to data availability)
1.2.8.4 R&D Investment (Subject to data availability)
1.2.8.5 Product Types Specification
1.2.8.6 Business Strategy
1.2.8.7 Recent Developments
1.2.8.8 Management Change
1.2.8.9 S.W.O.T Analysis
1.2.9 Resideo Technologies
1.2.9.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.9.2 Business Overview
1.2.9.3 Financials (Subject to data availability)
1.2.9.4 R&D Investment (Subject to data availability)
1.2.9.5 Product Types Specification
1.2.9.6 Business Strategy
1.2.9.7 Recent Developments
1.2.9.8 Management Change
1.2.9.9 S.W.O.T Analysis
1.2.10 Cerner Corporation
1.2.10.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.10.2 Business Overview
1.2.10.3 Financials (Subject to data availability)
1.2.10.4 R&D Investment (Subject to data availability)
1.2.10.5 Product Types Specification
1.2.10.6 Business Strategy
1.2.10.7 Recent Developments
1.2.10.8 Management Change
1.2.10.9 S.W.O.T Analysis
Chapter 2. Global Telehealth Technology Market Analysis
2.1 Global Telehealth Technology Market Analysis
2.2 Global Telehealth Technology Market Analysis by Region
2.3 Global Telehealth Technology Market Analysis by Type
2.4 Global Telehealth Technology Market Analysis by Application
2.5 Global Telehealth Technology Market Analysis by Key Players
Chapter 3. North America Telehealth Technology Market Analysis
3.1 North America Telehealth Technology Market Analysis
3.2 North America Telehealth Technology Market Analysis by Country
3.3 North America Telehealth Technology Market Analysis by Type
3.4 North America Telehealth Technology Market Analysis by Application
3.5 North America Telehealth Technology Market Analysis by Key Players
Chapter 4. Europe Telehealth Technology Market Analysis
4.1 Europe Telehealth Technology Market Analysis
4.2 Europe Telehealth Technology Market Analysis by Country
4.3 Europe Telehealth Technology Market Analysis by Type
4.4 Europe Telehealth Technology Market Analysis by Application
4.5 Europe Telehealth Technology Market Analysis by Key Players
Chapter 5. Asia Pacific Telehealth Technology Market Analysis
5.1 Asia Pacific Telehealth Technology Market Analysis
5.2 Asia Pacific Telehealth Technology Market Analysis by Country
5.3 Asia Pacific Telehealth Technology Market Analysis by Type
5.4 Asia Pacific Telehealth Technology Market Analysis by Application
5.5 Asia Pacific Telehealth Technology Market Analysis by Key Players
Chapter 6. South America Telehealth Technology Market Analysis
6.1 South America Telehealth Technology Market Analysis
6.2 South America Telehealth Technology Market Analysis by Country
6.3 South America Telehealth Technology Market Analysis by Type
6.4 South America Telehealth Technology Market Analysis by Application
6.5 South America Telehealth Technology Market Analysis by Key Players
Chapter 7. Middle East Telehealth Technology Market Analysis
7.1 Middle East Telehealth Technology Market Analysis
7.2 Middle East Telehealth Technology Market Analysis by Country
7.3 Middle East Telehealth Technology Market Analysis by Type
7.4 Middle East Telehealth Technology Market Analysis by Application
7.5 Middle East Telehealth Technology Market Analysis by Key Players
Chapter 8. Africa Telehealth Technology Market Analysis
8.1 Africa Telehealth Technology Market Analysis
8.2 Africa Telehealth Technology Market Analysis by Country
8.3 Africa Telehealth Technology Market Analysis by Type
8.4 Africa Telehealth Technology Market Analysis by Application
8.5 Africa Telehealth Technology Market Analysis by Key Players
Chapter 9. Type Analysis
9.1 Software
9.1.1 Global Software Market
9.1.2 Global Software Market by Region
9.2 Hardware
9.2.1 Global Hardware Market
9.2.2 Global Hardware Market by Region
9.3 Service
9.3.1 Global Service Market
9.3.2 Global Service Market by Region
Chapter 10. Application Analysis
10.1 Hospitals
10.1.1 Global Hospitals Market
10.1.2 Global Hospitals Market by Region
10.2 Clinics
10.2.1 Global Clinics Market
10.2.2 Global Clinics Market by Region
10.3 Diagnostic Centers
10.3.1 Global Diagnostic Centers Market
10.3.2 Global Diagnostic Centers Market by Region
10.4 Others
10.4.1 Global Others Market
10.4.2 Global Others Market by Region
Chapter 11. Qualitative Analysis (Subject to Data Availability)
11.1 Market Drivers
11.2 Market Restraints
11.3 Market Trends
11.4 Market Opportunity
11.5 Technological Road Map (Subject to Data Availability)
11.6 Product Life Cycle (Subject to Data Availability)
11.7 Customer and Buyer Behavior Analysis
11.7.1 Digital Engagement, Customer Experience & Relationship Analysis
11.14.2 AI-Driven Transformation of Industry Value Chain
11.14.3 Evolution of Business Models & Revenue Streams
11.14.4 AI-Driven Product, Service & Innovation Transformation
11.14.5 Customer Behavior, AI Adoption & Future Market Evolution
Chapter 12. TOP 10 Country Analysis
12.1 Country 1
12.2 Country 2
12.3 Country 3
12.4 Country 4
12.5 Country 5
12.6 Country 6
12.7 Country 7
12.8 Country 8
12.9 Country 9
12.10 Country 10
Chapter 13. Research Findings
13.1 Key Takeaways
13.2 Analyst Point of View
13.3 Assumptions and Acronyms
Chapter 14. Research Methodology and Sources
14.1 Primary Data Collection
14.1.1 Steps for Primary Data Collection
14.1.1.1 Identification of KOL
14.1.2 Backward Integration
14.1.3 Forward Integration
14.1.4 How Primary Research Help Us
14.1.5 Modes of Primary Research
14.2 Secondary Research
14.2.1 How Secondary Research Help Us
14.2.2 Sources of Secondary Research
14.3 Data Validation
14.3.1 Data Triangulation
14.4 Data Representation
Athenaeum AI Dashboard
Research Framework · 70:30 Primary:Secondary
Our Proprietary Methodology
Cognitive Market Research and Consulting "The Full Truth" methodology — a rigorous triangulation process that combines primary research, secondary validation, and expert calibration. Implemented by Supriya Yadav and team for the Telehealth Technology Market Analysis Market analysis.
01
Primary Intelligence Gathering
Direct interviews with 50+ industry stakeholders including manufacturers, distributors, end-users, and regulatory bodies across all six regions.
02
Secondary Data Triangulation
Cross-referencing against trade databases, customs records, financial filings, patent databases, and verified industry publications.
03
Expert Validation Protocol
Each data point undergoes validation by minimum two independent domain experts with 15+ years of industry experience.
04
Athenaeum AI Processing
Our proprietary AI platform aggregates, normalizes, and identifies patterns across 10,000+ data points to surface non-obvious insights.
05
Editorial & QA Review
Final review by senior analysts ensures accuracy, coherence, and actionability of all insights and recommendations.
To maintain the integrity of our proprietary methodology and protect our elite expert network, specific source disclosures are reserved for full-access partners. Our research framework is anchored by a 70:30 primary-to-secondary ratio, ensuring your strategy is driven by real-time market intelligence rather than recycled, publicly available, or AI-generated data. Every deliverable includes an exhaustive source directory and grants direct analyst access.
Latest News about Telehealth Technology Market
25 Apr 2024businesstoday.in
Healthify VP Abhijit Khasnis on partnership with OpenAI and keeping your health in check with tech
Healthify, a renowned Indian health-tech startup, has collaborated with OpenAI to create breakthrough AI models. Abhijit Khasnis, Healthify's VP of Technology, is managing the integration of OpenAI's GPT models into the company's products. The collaboration has resulted in the creation of unique features and recognition within the IT community. Healthify has developed ground-breaking products such as Ria, an AI-powered wellness assistant. OpenAI has recognised Healthify's use of Generative AI models in consumer-facing products, including the Snap product, which automates nutritional tracking. This acknowledgment not only reinforces Healthify's position as a leader, but it also opens the door to new collaborations, investments, and development prospects. The cooperation is further bolstered by Healthify's presence in India, where OpenAI has its second-biggest user base and Healthify is the country's largest health tech company.
The Three Pillars of End-to-End Market Research Services
We don't just hand over data. We partner with your team across three integrated service lines — each designed to give you decision-grade intelligence on the Telehealth Technology Market Analysis market.
Service 01
Market Survey
B2BB2C
Structured primary research across both B2B and B2C channels. We design and execute custom surveys targeting manufacturers, distributors, procurement heads, and end-consumers in the telehealth technology market analysis ecosystem — validated by our global panel of 10,000+ industrial respondents.
What's Included
Buyer intent & sentiment analysis
Purchase cycle mapping
Price sensitivity research
Channel preference profiling
Competitive perception study
Most Requested
Service 02
Customized Market Data & Reports
CustomReady Report
Choose from our ready-to-access 8th Edition report or commission a fully customized dataset tailored to your exact strategic questions. Cross-splits, custom geographies, proprietary segmentation — we build the intelligence asset your board actually needs.
What's Included
Ready syndicate report
Custom data scope & segmentation
Excel quantitative models
Board-ready PPT with key findings
Secure cloud portal access
Service 03
Strategic Consultation
With SurveyWith Report
Every survey and every report comes with dedicated analyst consultation. Our senior research team walks your leadership through findings, answers strategic questions in real-time, and helps translate data into your next board presentation or investment thesis.
Tell us the specific segments, regions, or companies you need — and we will tailor the deliverable to your requirements.
Why Trust Us
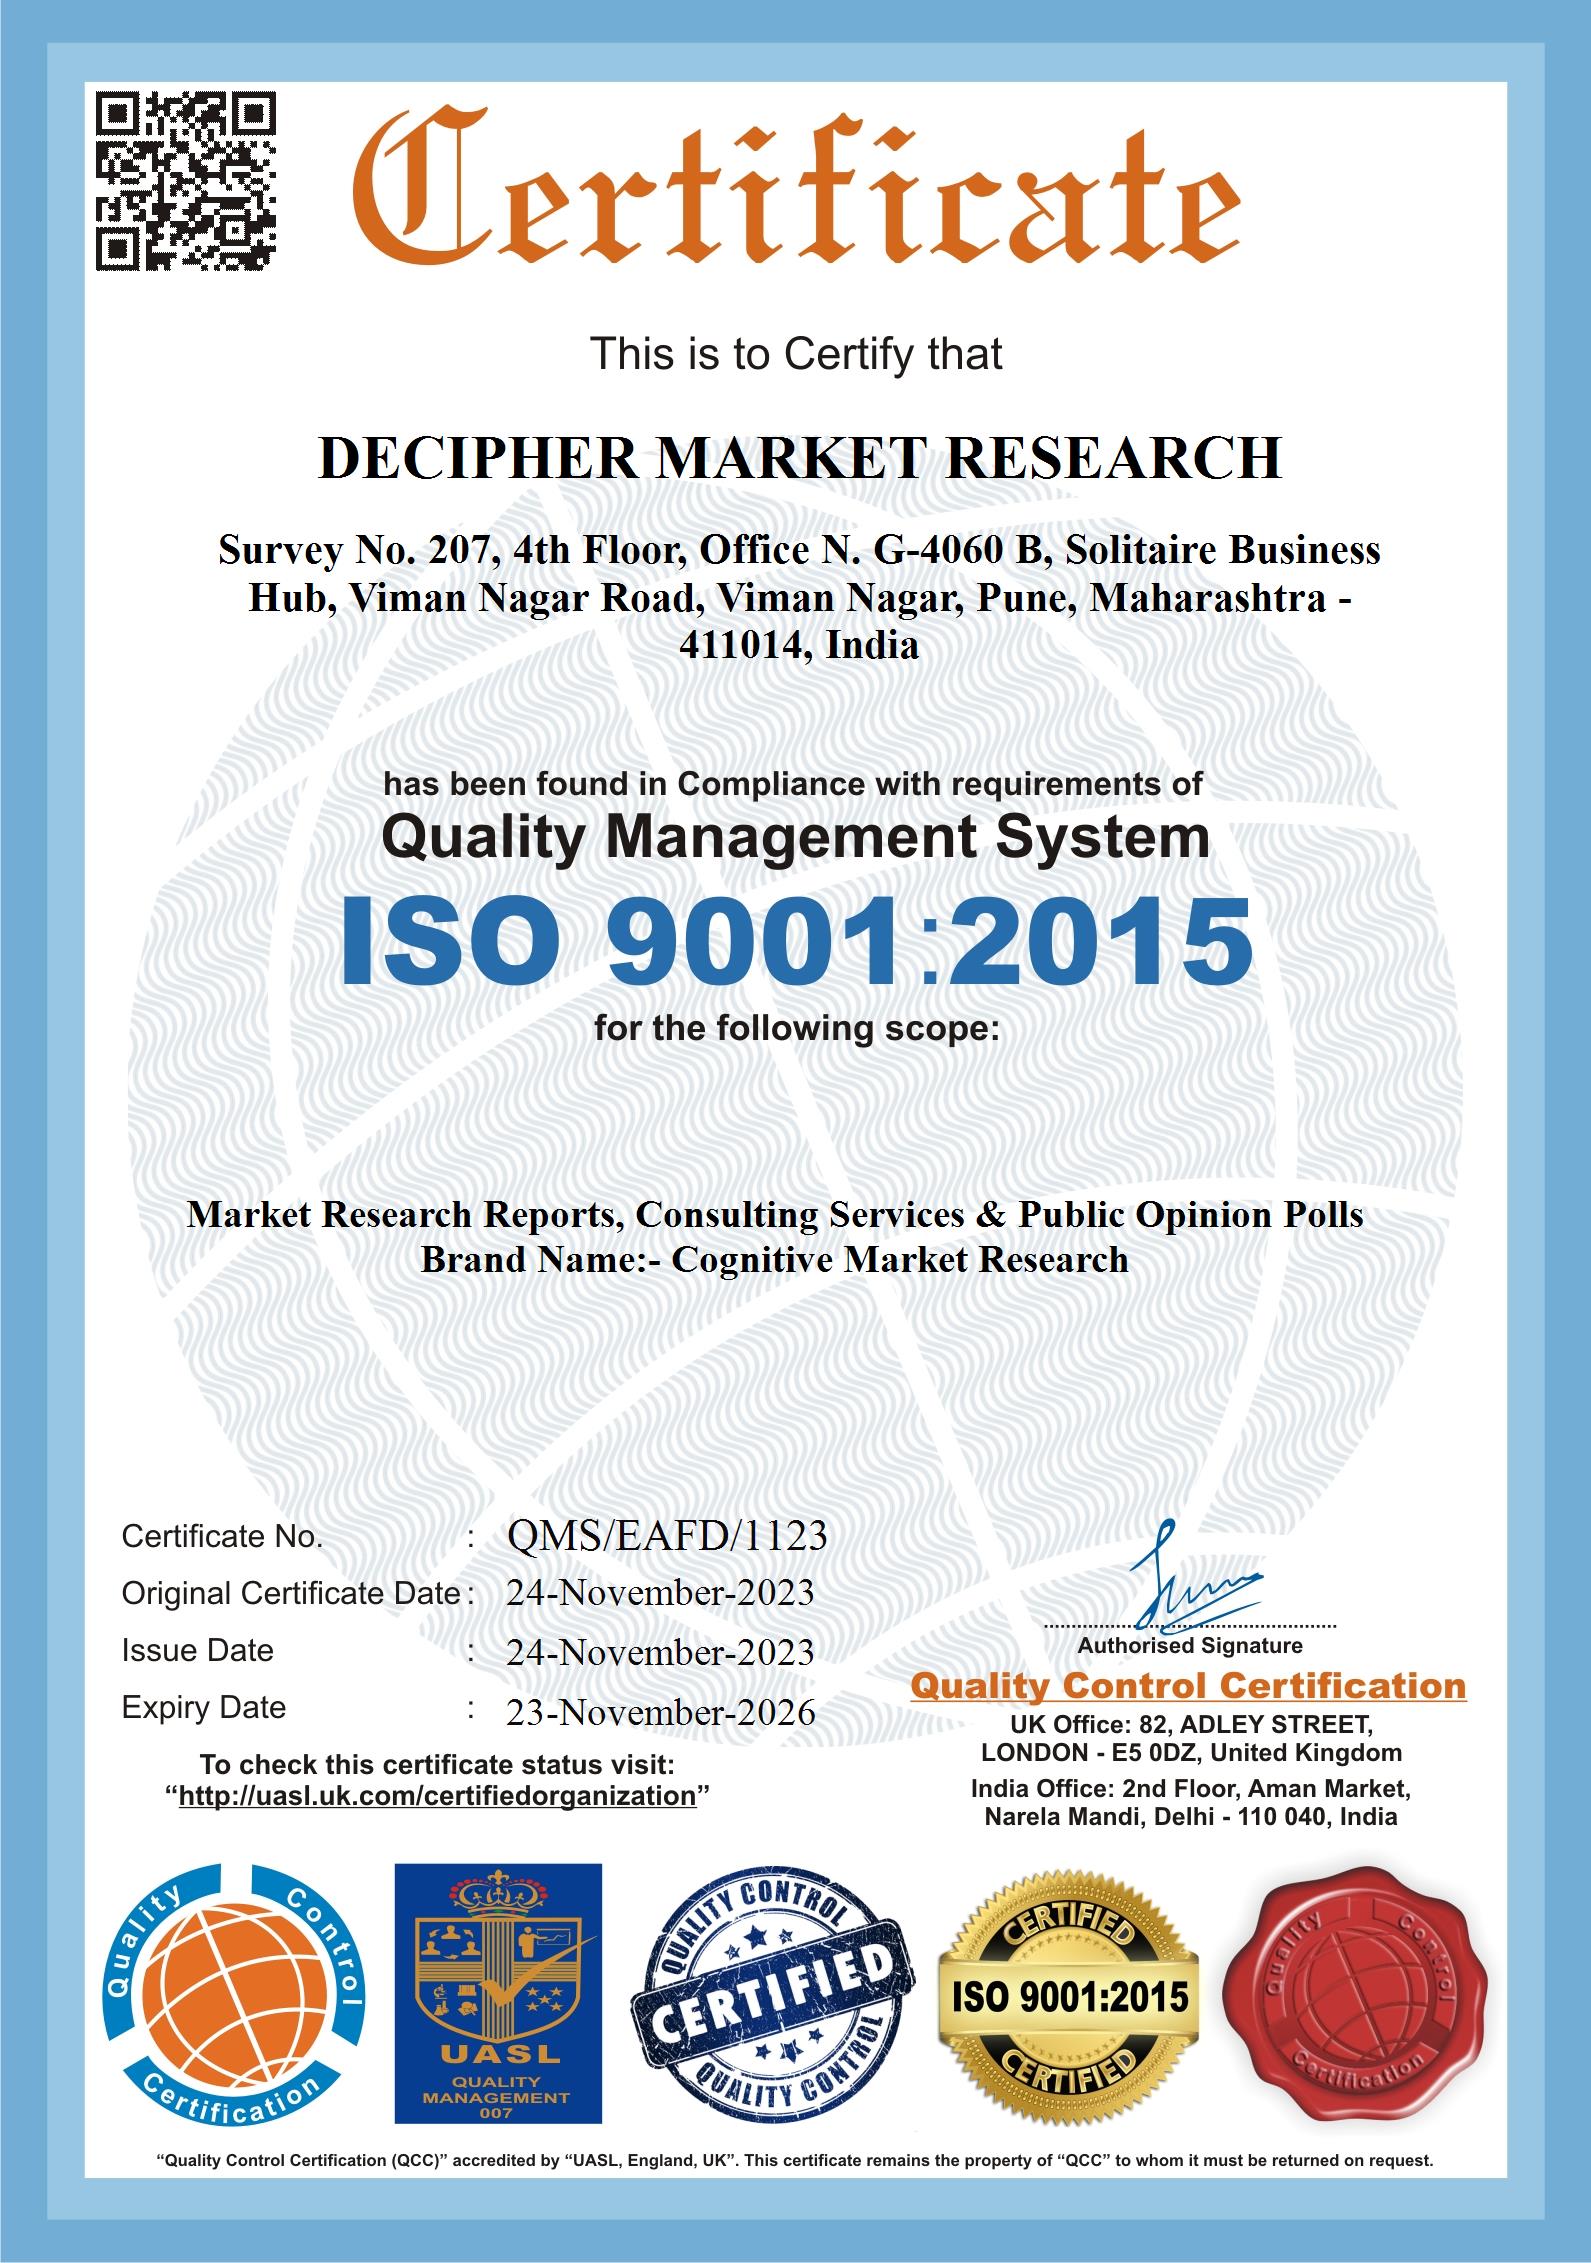
What these certifications mean to usA market figure is only as reliable as the system that produced it. That is why our accreditations cover the whole chain, not just the research step. ESOMAR and MRSI membership binds us to the professional codes that govern how respondents are recruited and how findings may be represented. ISO 20252 governs the research process itself; ISO 9001 and our quality control certification govern how consistently we repeat it. ISO 27001 and ISO 27701, alongside our GDPR, CCPA and DPDP compliance, govern what happens to your brief and your data once it reaches us; because a confidential scope is often more sensitive than the deliverable. ISO 14001, our D-U-N-S registration, Chamber of Commerce membership and DMCA protection speak to how the company itself is run and how its work is safeguarded.Our Clutch and Trustpilot profiles are deliberately listed next to them. They are the only signals on this page we do not issue ourselves, and they are the ones we would check first if we were you.
I enjoyed reviewing all the contents of the report. I am wondering if you can generate similar reports for Orlistat and Mounjaro as you have provided for o…
The telehealth market is set for explosive and sustained growth, with a global CAGR of 24.325% transforming it from a $64.376 billion market in 2021 into an $877.858 billion industry by 2033, underscoring its pivotal role in the future of healthcare.
North America and Europe are the current market leaders in terms of value, but the highest growth rates are found in Asia-Pacific (25.777% CAGR) and South America (25.463% CAGR), signaling a geographic shift in market opportunities.
Country-level dynamics reveal diverse growth stories. While the U.S. remains the single largest market, nations like India (26.676% CAGR), Singapore (29.5% CAGR), and Egypt (29.389% CAGR) are experiencing exceptionally rapid adoption, presenting unique opportunities for tailored market-entry strategies.
Success in this evolving market hinges on overcoming key challenges. Manufacturers and providers must navigate a complex web of regional regulations, address critical data security concerns, and design accessible, user-friendly technologies to bridge the digital divide and ensure equitable access to care.