We value your privacy
We use cookies to improve your experience and analyze traffic. By continuing, you consent to our use of cookies under GDPR, CCPA and other applicable laws. Privacy Policy
Cookie preferences
Choose which categories of cookies you allow. Strictly necessary cookies are always on.
Strictly necessary
Required for core site functionality, security and your session. Always active.
Analytics
Help us understand how visitors use the site (e.g. Google Analytics) so we can improve it.
Marketing
Used to measure campaigns and show you relevant ads on other sites (e.g. LinkedIn, Google Ads).
Specialty Vinyl Ester Resin Market Analysis size 2021 was recorded $1004.7 Million whereas by the end of 2026 it will reach $1376.42 Million. According to the author, by 2033 Specialty Vinyl Ester Resin market size will become $2139.09 Million. Specialty Vinyl Ester Resin market will be growing at a CAGR of 6.5% during 2026 to 2033. Download a free sample with data verified by Chidanand Bilagi
Global Specialty Vinyl Ester Resin Market Analysis 2026
Country-level values are locked in this preview.
Request a free sample
to unlock the full breakdown.
Region / Country
2021 (A)
2025 (A)
2033 (P)
CAGR
Global
$ 1004.7 Million
$ 1292.51 Million
$ 2139.09 Million
6.5%
North America
$ 289.35 Million
$ 365.66 Million
$ 583.97 Million
6.026%
United States
$ 254.34 Million
$ 318.47 Million
$ 499.3 Million
5.782%
Canada
$ 28.07 Million
$ 38.7 Million
$ 73.58 Million
8.363%
Mexico
$ 6.94 Million
$ 8.5 Million
$ 11.1 Million
3.392%
Europe
$ 247.16 Million
$ 310.91 Million
$ 491.99 Million
5.905%
United Kingdom
$ 32.62 Million
$ 39.87 Million
$ 59.58 Million
5.151%
France
$ 36.09 Million
$ 45.7 Million
$ 73.31 Million
6.084%
Germany
$ 46.47 Million
$ 58.03 Million
$ 90.53 Million
5.715%
Italy
$ 25.7 Million
$ 33.04 Million
$ 54.61 Million
6.481%
Russia
$ 23.48 Million
$ 30.73 Million
$ 52.64 Million
6.96%
Spain
$ 18.54 Million
$ 24.12 Million
$ 40.84 Million
6.803%
Sweden
$ 15.82 Million
$ 19.48 Million
$ 29.52 Million
5.337%
Denmark
$ 8.9 Million
$ 10.87 Million
$ 16.24 Million
5.14%
Switzerland
$ 16.81 Million
$ 21.04 Million
$ 32.96 Million
5.774%
Luxembourg
$ 9.89 Million
$ 12.02 Million
$ 17.76 Million
5.003%
Rest of Europe
$ 12.85 Million
$ 16.01 Million
$ 24.01 Million
5.196%
Asia Pacific
$ 329.54 Million
$ 433.42 Million
$ 749.75 Million
7.09%
China
$ 104.14 Million
$ 135.35 Million
$ 228.67 Million
6.775%
Japan
$ 59.65 Million
$ 76.37 Million
$ 125.21 Million
6.374%
South Korea
$ 33.94 Million
$ 43.91 Million
$ 73.48 Million
6.647%
India
$ 52.73 Million
$ 74.08 Million
$ 146.2 Million
8.871%
Australia
$ 25.7 Million
$ 34.38 Million
$ 61.48 Million
7.538%
Singapore
$ 18.45 Million
$ 24.77 Million
$ 44.61 Million
7.633%
Taiwan
$ 10.55 Million
$ 13.5 Million
$ 22.12 Million
6.367%
South East Asia
$ 13.51 Million
$ 17.25 Million
$ 28.12 Million
6.297%
Rest of APAC
xxxx
xxxx
xxxx
xxxx
South America
$ 69.32 Million
$ 89.83 Million
$ 150.81 Million
6.691%
Brazil
$ 29.6 Million
$ 38.21 Million
$ 63.64 Million
6.586%
Argentina
$ 14.14 Million
$ 18.71 Million
$ 32.73 Million
7.242%
Colombia
$ 9.88 Million
$ 13.06 Million
$ 22.85 Million
7.237%
Peru
$ 6.52 Million
$ 8.31 Million
$ 13.5 Million
6.256%
Chile
$ 5.23 Million
$ 6.69 Million
$ 10.93 Million
6.331%
Rest of South America
$ 3.95 Million
$ 4.85 Million
$ 7.16 Million
4.987%
Middle East
$ 41.19 Million
$ 54.66 Million
$ 96.26 Million
7.329%
Saudi Arabia
$ 12.28 Million
$ 16.2 Million
$ 28.2 Million
7.178%
Turkey
$ 7.83 Million
$ 10.34 Million
$ 18.04 Million
7.206%
UAE
$ 6.47 Million
$ 8.95 Million
$ 17.13 Million
8.458%
Egypt
$ 5.27 Million
$ 7.02 Million
$ 12.48 Million
7.447%
Qatar
$ 3.75 Million
$ 4.88 Million
$ 8.28 Million
6.825%
Rest of Middle East
$ 5.6 Million
$ 7.27 Million
$ 12.13 Million
6.6%
Africa
$ 28.13 Million
$ 38.03 Million
$ 66.31 Million
7.199%
East Africa
xxxx
xxxx
xxxx
xxxx
West Africa
xxxx
xxxx
xxxx
xxxx
North Africa
xxxx
xxxx
xxxx
xxxx
South Africa
$ 8.5 Million
$ 11.75 Million
$ 21.43 Million
7.804%
The Specialty Vinyl Ester Resin market is characterized by its critical role in providing corrosion resistance and structural integrity in demanding industrial applications. These thermosetting resins, which offer a balance of performance between polyester and epoxy resins, are vital for manufacturing fiber-reinforced plastics (FRP) and composites. The market dynamics are strongly influenced by the health of the global industrial sector, infrastructure spending, and environmental policies. While Asia Pacific dominates due to its manufacturing prowess, North America and Europe remain significant markets focused on high-value, specialized applications and retrofitting existing infrastructure.
Global Specialty Vinyl Ester Resin Market Drivers
Superior Corrosion and Chemical Resistance: The primary driver is the exceptional ability of specialty vinyl ester resins to withstand a wide range of acids, alkalis, and solvents. This makes them indispensable for equipment like storage tanks, pipes, and reactors in the chemical processing, oil and gas, and water treatment industries, extending the service life of assets and reducing maintenance costs.
Growing Demand for Fiber-Reinforced Plastics (FRP): The increasing use of lightweight, high-strength FRP composites as a substitute for traditional materials like steel, aluminum, and concrete is propelling market growth. Vinyl ester resins are a key matrix material for these composites, which are used extensively in construction, transportation, and wind energy applications (e.g., turbine blades).
Infrastructure Development and Rehabilitation in Emerging Economies: Rapid industrialization and urbanization in regions like Asia Pacific and the Middle East are fueling massive investments in new infrastructure, including industrial plants, water treatment facilities, and bridges. Specialty vinyl ester resins are crucial for ensuring the long-term durability and safety of this infrastructure.
Global Specialty Vinyl Ester Resin Market Trends
Development of Eco-Friendly and Bio-Based Resins: Growing environmental concerns and stringent regulations regarding Volatile Organic Compound (VOC) emissions are pushing manufacturers to develop low-styrene, styrene-free, and bio-based vinyl ester resins. This trend is opening new avenues for sustainable products that meet green building standards.
Increasing Adoption in the Wind Energy Sector: The global push towards renewable energy has boosted the demand for wind turbines. Specialty vinyl ester resins are increasingly used in the manufacturing of long, durable, and lightweight wind turbine blades due to their excellent fatigue resistance and mechanical properties.
Focus on High-Performance and Niche Applications: There is a growing trend towards developing highly specialized formulations, such as fire-retardant, high-temperature resistant, and toughened vinyl ester resins. These products cater to niche, high-value applications in the aerospace, defense, and electronics industries, commanding premium prices.
Global Specialty Vinyl Ester Resin Market Restraints
Volatility in Raw Material Prices: The market is highly susceptible to price fluctuations of key raw materials, particularly epoxy resins and styrene monomer, which are derived from crude oil. This volatility can impact production costs and profit margins for manufacturers, creating market instability.
Competition from Alternative Resins: Specialty vinyl ester resins face competition from other high-performance resins, such as advanced epoxy resins, polyurethanes, and certain high-grade polyesters. The choice of resin often depends on a specific cost-performance balance for a given application, and in some cases, alternatives may be preferred.
Stringent Environmental and Health Regulations: Regulations concerning the handling and emission of styrene, a key component in most standard vinyl ester resins, pose a significant challenge. Compliance requires investment in emission control technologies and drives the costly development of safer, low-VOC alternatives.
Market Size: $ 289.352 Million (2021) -> $ 365.664 Million (2025) -> $ 583.972 Million (2033)
CAGR (2021-2033): 6.026%
Country-Specific Insight: North America holds a significant 28.29% of the global market in 2025. The United States is the dominant force, accounting for 24.64% of the global market share in 2025, driven by its large industrial base and infrastructure renewal projects. Canada contributes approximately 2.99% to the global market, with demand from its oil & gas and mining sectors.
Key Drivers
Strong emphasis on repairing and retrofitting aging infrastructure, particularly water pipes, bridges, and chemical plants.
Stringent environmental regulations (e.g., from the EPA) favoring the use of durable, corrosion-resistant materials to prevent leaks and spills.
Established industrial base in chemical processing, pulp and paper, and power generation that consistently requires high-performance materials.
Key Trends
Growing adoption in the aerospace and defense sectors for composite parts.
Increased focus on low-VOC and HAP-free (Hazardous Air Pollutant) formulations to comply with clean air regulations.
Rising demand for fire-retardant vinyl ester resins for use in public transportation and building & construction.
Key Restraints
Market maturity in some end-use sectors, leading to slower growth compared to emerging regions.
High labor costs for composite fabrication can make FRP solutions less competitive against traditional materials in some applications.
Intense competition from well-established epoxy resin manufacturers.
Technology Focus
The technological focus in North America is on developing advanced composites with enhanced properties, such as improved toughness and fatigue resistance for applications like wind blades and automotive components. There is also a significant push towards automated manufacturing processes like pultrusion and filament winding to improve efficiency and reduce costs.
Market Size: $ 247.155 Million (2021) -> $ 310.908 Million (2025) -> $ 491.991 Million (2033)
CAGR (2021-2033): 5.905%
Country-Specific Insight: Europe accounts for approximately 24.05% of the global market in 2025. Germany is the regional leader, holding about 4.49% of the global market due to its strong chemical and automotive industries. France (3.54%), the United Kingdom (3.08%), and Italy (6.481%) are other key markets, driven by industrial manufacturing and infrastructure projects.
Key Drivers
Strict EU regulations like REACH, which drive the adoption of high-performance and safer chemical-resistant materials.
Strong government support and investment in renewable energy, particularly offshore wind farms, boosting demand for composite turbine blades.
A well-developed chemical industry that requires robust materials for corrosion protection in aggressive environments.
Key Trends
Strong push towards a circular economy, encouraging research into recyclable thermoset composites and bio-based resins.
Increasing use of vinyl ester-based composites in the automotive sector for lightweighting vehicles to improve fuel efficiency and reduce emissions.
Adoption of infusion and RTM (Resin Transfer Molding) processes for high-quality, large-scale composite part production.
Key Restraints
Economic uncertainties and slower industrial growth in some parts of Europe compared to Asia.
High energy and regulatory compliance costs can impact the competitiveness of European manufacturers.
Strong preference for epoxy resins in certain high-tech applications like aerospace.
Technology Focus
The technology focus is heavily skewed towards sustainability. European companies are at the forefront of developing and commercializing bio-based vinyl ester resins derived from renewable feedstocks and creating formulations that are compliant with the most stringent environmental standards, such as those with zero styrene content.
Market Size: $ 329.54 Million (2021) -> $ 433.422 Million (2025) -> $ 749.752 Million (2033)
CAGR (2021-2033): 7.09%
Country-Specific Insight: Asia Pacific is the largest market, commanding 33.53% of the global share in 2025. China is the dominant market player, holding 10.47% of the global market, followed by Japan (5.91%) and India (5.73%). The rapid industrial and infrastructural growth in these countries is the primary factor behind the region's leadership.
Key Drivers
Massive government and private investment in infrastructure projects, including water treatment plants, chemical facilities, and transportation networks.
Rapidly expanding manufacturing sector, which increases the demand for durable industrial equipment and components.
Growing environmental awareness and nascent regulations for pollution control, leading to the construction of Flue Gas Desulfurization (FGD) systems, a major application for vinyl ester resins.
Key Trends
A shift from low-cost general-purpose resins to higher-performance specialty resins as quality and durability standards improve.
Local manufacturers are increasing their production capacity and technological capabilities to compete with global players.
Increasing application in the electronics industry for corrosion-proof components and casings.
Key Restraints
Intense price competition among a large number of local and regional suppliers, which can erode profit margins.
Inconsistent implementation of environmental regulations across different countries.
Lack of awareness and technical expertise in advanced composite applications in some developing parts of the region.
Technology Focus
The technology focus in APAC is on scaling up production capacity and improving process efficiency to achieve cost-effective manufacturing. There is also a growing interest in adopting technologies for producing higher-performance grades to serve the region's burgeoning high-tech industries, such as electronics and renewable energy.
Market Size: $ 69.324 Million (2021) -> $ 89.825 Million (2025) -> $ 150.806 Million (2033)
CAGR (2021-2033): 6.691%
Country-Specific Insight: South America constitutes around 6.95% of the global market in 2025. Brazil is the largest market in the region, holding approximately 2.96% of the global share, with its significant industrial and mining sectors. Argentina follows, accounting for about 1.45% of the global market, with growth tied to its oil & gas and agricultural sectors.
Key Drivers
Growth in the mining and minerals processing industries, which require highly corrosion-resistant tanks, pipes, and electrolytic cells.
Expansion of the oil and gas sector, driving demand for corrosion-resistant equipment for exploration, transportation, and refining.
Investments in public sanitation and water treatment infrastructure to serve a growing population.
Key Trends
Gradual replacement of traditional materials like coated steel with more durable and low-maintenance FRP composites.
Growing use in the agriculture sector for durable storage tanks for fertilizers and chemicals.
Increased local production and formulation of resins to cater to specific regional needs.
Key Restraints
Economic and political instability in several countries can deter foreign investment and delay major projects.
Logistical and supply chain challenges, including high import tariffs on raw materials.
Slower adoption of advanced composite technologies compared to developed regions.
Technology Focus
The technology focus is on the adoption and application of established vinyl ester resin technologies for core industrial applications. The emphasis is less on cutting-edge research and more on practical, cost-effective solutions for corrosion control in the region's primary industries like mining and oil and gas.
Market Size: $ 41.192 Million (2021) -> $ 54.663 Million (2025) -> $ 96.259 Million (2033)
CAGR (2021-2033): 7.329%
Country-Specific Insight: The Middle East accounts for 4.23% of the global market in 2025, with strong growth prospects. Saudi Arabia leads the region, holding 1.25% of the global share, driven by its massive investments in chemical and petrochemical plants. The UAE, with its focus on infrastructure and desalination, holds a 0.69% global share.
Key Drivers
Huge investments in the oil, gas, and petrochemical industries, which require materials resistant to extreme temperatures and corrosive chemicals.
The world's largest concentration of desalination plants, a key application area for vinyl ester resins in pipes, tanks, and vessels.
Economic diversification initiatives leading to the construction of new industrial cities and infrastructure.
Key Trends
Growing demand for high-temperature resistant vinyl ester resins for applications in the hot climate.
Increased use of pull-wound and filament-wound FRP pipes for water and oil transportation.
Adoption of international standards for quality and safety, driving the use of certified, high-performance materials.
Key Restraints
Geopolitical tensions and regional conflicts can disrupt projects and supply chains.
Heavy reliance on expatriate labor and expertise for advanced technical applications.
Strong competition from global suppliers who have a well-established presence in the region.
Technology Focus
Technology in the Middle East is focused on sourcing and applying the best-in-class, high-performance resins capable of withstanding the region's extreme environmental and industrial conditions. The emphasis is on formulations with superior thermal stability and resistance to highly corrosive substances like wet chlorine and crude oil.
Market Size: $ 28.131 Million (2021) -> $ 38.025 Million (2025) -> $ 66.312 Million (2033)
CAGR (2021-2033): 7.199%
Country-Specific Insight: Africa is an emerging market, representing about 2.94% of the global share in 2025. Growth is concentrated in countries with significant industrial activity, such as Nigeria, which holds 1.46% of the global market due to its oil and gas industry, and South Africa, which accounts for 0.91% with its developed mining and industrial sectors.
Key Drivers
Untapped potential in infrastructure development, including water, sanitation, and power generation.
Richness in natural resources, driving growth in the mining and oil & gas industries, which are key end-users.
Growing foreign investment aimed at developing the continent's industrial capabilities.
Key Trends
Increasing use of FRP for small-scale applications like water storage tanks and corrosion-resistant coatings.
Adoption of basic composite manufacturing techniques like hand lay-up for local fabrication.
A slow but steady shift towards materials that offer better long-term performance and lower life-cycle costs.
Key Restraints
Significant lack of infrastructure and skilled labor for advanced manufacturing.
Political and economic instability in many parts of the continent.
Low awareness of the benefits of advanced materials like specialty vinyl ester resins.
Technology Focus
The technology focus in Africa is nascent and centers on fundamental applications. The priority is on introducing basic, robust, and easy-to-use resin systems for essential applications like corrosion-resistant coatings and simple FRP structures, rather than on high-tech or specialized formulations.
A = Actual · E = Estimated · P = Projected · 🔒 Locked values require full access. Click headers to sort.
Disclaimer: The charts and graphs are for illustrative purposes only and do not represent actual market values. To access accurate quantitative data, please request a paid report or request free sample.
To learn more about market share and segmentation, request the free sample pages.
Competitor Analysis
Click any bar or cell to request the full company profile
Top Companies (In no particular order)
2022 (A)
2023 (A)
2024 (A)
2025 (A)
Swancor
•••
•••
•••
•••
Sino Polymer
•••
•••
•••
•••
Fuchem
•••
•••
•••
•••
Ashland
•••
•••
•••
•••
DSM
•••
•••
•••
•••
Showa Denko
•••
•••
•••
•••
Showa Denko
•••
•••
•••
•••
We Provide Regional Breakdown of this Companies and Company specific to any Country, Region, Product/ service as well. We cover market share analysis for publicly listed companies as well as privately held companies, subject to data availability.
Executive Summary of Specialty Vinyl Ester Resin Market
The global Specialty Vinyl Ester Resin market is poised for robust growth, projected to expand from USD 1004.7 million in 2021 to USD 2139.09 million by 2033, registering a CAGR of 6.5%. This growth is primarily fueled by the increasing demand for high-performance, corrosion-resistant materials across various end-use industries. Key sectors such as chemical processing, water and wastewater treatment, infrastructure, and marine are increasingly adopting these resins for their superior durability, mechanical strength, and resistance to harsh chemical environments. The market is also benefiting from the trend of replacing traditional materials like steel and concrete in critical applications. Asia Pacific stands as the largest and fastest-growing regional market, driven by rapid industrialization and significant infrastructure investments. The shift towards more sustainable, low-VOC, and bio-based formulations presents both a challenge and a significant opportunity for manufacturers.
Key strategic insights from our comprehensive analysis reveal:
The Asia Pacific region is the epicenter of market growth, commanding the largest market share and exhibiting the highest CAGR, propelled by burgeoning industrial and construction activities in China and India.
Innovation in product development is crucial, with a notable industry-wide trend towards developing bio-based and low-styrene/styrene-free vinyl ester resins to comply with stringent environmental regulations and meet consumer demand for sustainable solutions.
The market is driven by the intrinsic need for corrosion control in critical infrastructure, with applications in pipes, tanks, and flue gas desulfurization (FGD) linings being major consumers of specialty vinyl ester resins.
Strategic Recommendations for Manufacturers
Manufacturers should prioritize investment in R&D to expand their portfolio of green and sustainable products, such as bio-based and low-VOC specialty vinyl ester resins. Focusing on geographic expansion, particularly in the high-growth APAC and Middle East markets, through strategic partnerships or direct investment is critical. Furthermore, diversifying application focus into high-potential sectors like renewable energy (wind turbine blades), advanced composites for electric vehicles, and infrastructure rehabilitation will unlock new revenue streams and mitigate risks associated with reliance on traditional sectors.
This section explores the key market dynamics for Specialty Vinyl Ester Resin Market Analysis within the chemical industry. Our analysis details the primary drivers, restraints, opportunities, and the technological roadmap shaping the sector. We examine how factors like raw material availability, economic conditions, and stringent environmental and safety regulations impact the production, pricing, and distribution of chemicals. This intelligence helps businesses understand current market conditions and technological advancements, enabling informed strategic planning in a complex regulatory environment.
Analyst Conclusion
As per Cognitive's Research Analyst, Specialty Vinyl Ester Resin are thermosetting resins that provide corrosion resistance and structural integrity in demanding industrial applications, vital for manufacturing fiber-reinforced plastics (FRP) and composites. They play an essential role in providing superior durability, mechanical strength, and resistance to harsh chemical environments in applications such as chemical processing, water and wastewater treatment, infrastructure, and marine sectors.
Looking at the Historical Growth The global market expanded from $1004.7 million in 2021 to an estimated $1376.42 million in 2026 due to the increasing demand for high-performance, corrosion-resistant materials across various end-use industries. Regionally, Asia Pacific grew from $329.54 million in 2021 to $464.18 million in 2026, while North America progressed from $289.352 million to $387.70 million over the same period.
Currently in 2026, Asia Pacific holds a commanding 33.72% of the global market, driven by massive government and private investment in infrastructure projects. Corrosion control applications in critical infrastructure, such as pipes, tanks, and FGD linings, remain the primary consumer of Specialty Vinyl Ester Resin. Additionally Middle East is set to be the fastest-growing region, exhibiting the highest CAGR of 7.329%, fueled by huge investments in the oil, gas, and petrochemical industries requiring materials resistant to extreme temperatures and corrosive chemicals.
The market is witnessing a definitive shift towards sustainable, low-VOC, and bio-based formulations, driven by growing environmental concerns and stringent regulations regarding Volatile Organic Compound (VOC) emissions. Ongoing innovation in polymer technology and advanced material science is also leading, focusing on enhanced durability for demanding environments and improved sustainability through low-VOC and bio-based formulations.
In the future, The global Specialty Vinyl Ester Resin market will reach to $2139.09 million by 2033, expanding at a compound annual growth rate of 6.5% from 2021, primarily driven by expanding applications in chemical processing, water treatment, and the renewable energy sector, along with robust infrastructure development. Ongoing innovation in material science and composite manufacturing and the strong trend towards advancements in composite applications for diverse industries and the ongoing pursuit of eco-friendly solutions will also contribute significantly.
Senior Research Associate at Cognitive Market Research
Chidanand Bilagi is a Senior Research Associate at Cognitive Market Research and Consulting, specializing in the chemical and materials industry. With a strong focus on global chemical markets, advanced materials, specialty chemicals, sustainable materials, and emerging industrial innovations, he delivers in-depth market intelligence and strategic insights to support informed decision-making.
His expertise includes analyzing industry trends, competitive landscapes, supply chain dynamics, regulatory developments, raw material pricing patterns, and technological advancements shaping the future of the chemical and materials sector. Through rigorous research and data-driven analysis, Chidanand contributes to the development of comprehensive market reports, helping businesses, investors, and industry stakeholders identify opportunities and address challenges in an evolving global market landscape.
Specialty Vinyl Ester Resin Market Analysis market size and growth rate is provided in the report covering 2021-2025 historical and 2025-2033 forecast data.
Major factors including drivers, restraints, opportunities and challenges are analyzed with detailed insights.
Top manufacturers Swancor, Sino Polymer, Fuchem, Ashland, DSM, Showa Denko, Showa Denko and others are profiled in the report.
Segments include Type, Application and additional sub-segments.
Regional analysis covers all major markets. The report identifies the dominant region and provides country-level data.
Sample pages can be obtained on demand from the website. 24/7 chat support and direct call services are available.
★ Reviews
Rate this report
Specialty Vinyl Ester Resin Market Analysis — Table of Contents
Disclaimer:
This is just a redacted sample pages of the actual deliverable report and only for representative purposes
Charts/Graphs/Numbers/data are only for Representative purposes and do not depict actual statistics.
The table of Contents differs according to the user License selection. Current Displayed TOC is for the Corporate User License Report Edition. TOC Customization options: Add or Remove section/s Or chapter/s from the report.
Specific Tables, Graphs, Sections, and Chapters can be ordered at a discounted price.
If applicable; On Request Volume Data will also be provided (at an Additional Cost).
Report Scope
Type
Flame Retardant Epoxy Vinyl Ester, Phenolic Epoxy Vinyl Ester, High Crosslinking Density Epoxy Vinyl Ester, Flexible Epoxy Vinyl Ester, PU Modified Epoxy Vinyl Ester, Others
Application
FRP Products, Anti corrosion Coating, Others
List of Competitors
Swancor, Sino Polymer, Fuchem, Ashland, DSM, Showa Denko, Showa Denko
Chapter 1. Competitor Analysis (Subject to Data Availability (Private Players))
1.1 Top Competitors Analysis
1.1.1 Global Specialty Vinyl Ester Resin Market Analysis by Key Players
1.1.2 Segment Market Analysis by Key Players
1.1.3 Top Players Ranking 2024
1.1.4 New Product Launch Analysis
1.1.5 Industry Mergers and Acquisition Analysis
1.2 Company Profile (Data Subject to Availability) Sample Format
1.2.1 Swancor
1.2.1.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.1.2 Business Overview
1.2.1.3 Financials (Subject to data availability)
1.2.1.4 R&D Investment (Subject to data availability)
1.2.1.5 Product Types Specification
1.2.1.6 Business Strategy
1.2.1.7 Recent Developments
1.2.1.8 Management Change
1.2.1.9 S.W.O.T Analysis
1.2.2 Sino Polymer
1.2.2.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.2.2 Business Overview
1.2.2.3 Financials (Subject to data availability)
1.2.2.4 R&D Investment (Subject to data availability)
1.2.2.5 Product Types Specification
1.2.2.6 Business Strategy
1.2.2.7 Recent Developments
1.2.2.8 Management Change
1.2.2.9 S.W.O.T Analysis
1.2.3 Fuchem
1.2.3.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.3.2 Business Overview
1.2.3.3 Financials (Subject to data availability)
1.2.3.4 R&D Investment (Subject to data availability)
1.2.3.5 Product Types Specification
1.2.3.6 Business Strategy
1.2.3.7 Recent Developments
1.2.3.8 Management Change
1.2.3.9 S.W.O.T Analysis
1.2.4 Ashland
1.2.4.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.4.2 Business Overview
1.2.4.3 Financials (Subject to data availability)
1.2.4.4 R&D Investment (Subject to data availability)
1.2.4.5 Product Types Specification
1.2.4.6 Business Strategy
1.2.4.7 Recent Developments
1.2.4.8 Management Change
1.2.4.9 S.W.O.T Analysis
1.2.5 DSM
1.2.5.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.5.2 Business Overview
1.2.5.3 Financials (Subject to data availability)
1.2.5.4 R&D Investment (Subject to data availability)
1.2.5.5 Product Types Specification
1.2.5.6 Business Strategy
1.2.5.7 Recent Developments
1.2.5.8 Management Change
1.2.5.9 S.W.O.T Analysis
1.2.6 Showa Denko
1.2.6.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.6.2 Business Overview
1.2.6.3 Financials (Subject to data availability)
1.2.6.4 R&D Investment (Subject to data availability)
1.2.6.5 Product Types Specification
1.2.6.6 Business Strategy
1.2.6.7 Recent Developments
1.2.6.8 Management Change
1.2.6.9 S.W.O.T Analysis
1.2.7 Showa Denko
1.2.7.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.7.2 Business Overview
1.2.7.3 Financials (Subject to data availability)
1.2.7.4 R&D Investment (Subject to data availability)
1.2.7.5 Product Types Specification
1.2.7.6 Business Strategy
1.2.7.7 Recent Developments
1.2.7.8 Management Change
1.2.7.9 S.W.O.T Analysis
Chapter 2. Global Specialty Vinyl Ester Resin Market Analysis
2.1 Global Specialty Vinyl Ester Resin Market Analysis
2.2 Global Specialty Vinyl Ester Resin Market Analysis by Region
2.3 Global Specialty Vinyl Ester Resin Market Analysis by Type
2.4 Global Specialty Vinyl Ester Resin Market Analysis by Application
2.5 Global Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 3. North America Specialty Vinyl Ester Resin Market Analysis
3.1 North America Specialty Vinyl Ester Resin Market Analysis
3.2 North America Specialty Vinyl Ester Resin Market Analysis by Country
3.3 North America Specialty Vinyl Ester Resin Market Analysis by Type
3.4 North America Specialty Vinyl Ester Resin Market Analysis by Application
3.5 North America Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 4. Europe Specialty Vinyl Ester Resin Market Analysis
4.1 Europe Specialty Vinyl Ester Resin Market Analysis
4.2 Europe Specialty Vinyl Ester Resin Market Analysis by Country
4.3 Europe Specialty Vinyl Ester Resin Market Analysis by Type
4.4 Europe Specialty Vinyl Ester Resin Market Analysis by Application
4.5 Europe Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 5. Asia Pacific Specialty Vinyl Ester Resin Market Analysis
5.1 Asia Pacific Specialty Vinyl Ester Resin Market Analysis
5.2 Asia Pacific Specialty Vinyl Ester Resin Market Analysis by Country
5.3 Asia Pacific Specialty Vinyl Ester Resin Market Analysis by Type
5.4 Asia Pacific Specialty Vinyl Ester Resin Market Analysis by Application
5.5 Asia Pacific Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 6. South America Specialty Vinyl Ester Resin Market Analysis
6.1 South America Specialty Vinyl Ester Resin Market Analysis
6.2 South America Specialty Vinyl Ester Resin Market Analysis by Country
6.3 South America Specialty Vinyl Ester Resin Market Analysis by Type
6.4 South America Specialty Vinyl Ester Resin Market Analysis by Application
6.5 South America Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 7. Middle East Specialty Vinyl Ester Resin Market Analysis
7.1 Middle East Specialty Vinyl Ester Resin Market Analysis
7.2 Middle East Specialty Vinyl Ester Resin Market Analysis by Country
7.3 Middle East Specialty Vinyl Ester Resin Market Analysis by Type
7.4 Middle East Specialty Vinyl Ester Resin Market Analysis by Application
7.5 Middle East Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 8. Africa Specialty Vinyl Ester Resin Market Analysis
8.1 Africa Specialty Vinyl Ester Resin Market Analysis
8.2 Africa Specialty Vinyl Ester Resin Market Analysis by Country
8.3 Africa Specialty Vinyl Ester Resin Market Analysis by Type
8.4 Africa Specialty Vinyl Ester Resin Market Analysis by Application
8.5 Africa Specialty Vinyl Ester Resin Market Analysis by Key Players
Chapter 9. Type Analysis
9.1 Flame Retardant Epoxy Vinyl Ester
9.1.1 Global Flame Retardant Epoxy Vinyl Ester Market
9.1.2 Global Flame Retardant Epoxy Vinyl Ester Market by Region
9.2 Phenolic Epoxy Vinyl Ester
9.2.1 Global Phenolic Epoxy Vinyl Ester Market
9.2.2 Global Phenolic Epoxy Vinyl Ester Market by Region
9.3 High Crosslinking Density Epoxy Vinyl Ester
9.3.1 Global High Crosslinking Density Epoxy Vinyl Ester Market
9.3.2 Global High Crosslinking Density Epoxy Vinyl Ester Market by Region
9.4 Flexible Epoxy Vinyl Ester
9.4.1 Global Flexible Epoxy Vinyl Ester Market
9.4.2 Global Flexible Epoxy Vinyl Ester Market by Region
9.5 PU Modified Epoxy Vinyl Ester
9.5.1 Global PU Modified Epoxy Vinyl Ester Market
9.5.2 Global PU Modified Epoxy Vinyl Ester Market by Region
9.6 Others
9.6.1 Global Others Market
9.6.2 Global Others Market by Region
Chapter 10. Application Analysis
10.1 FRP Products
10.1.1 Global FRP Products Market
10.1.2 Global FRP Products Market by Region
10.2 Anti corrosion Coating
10.2.1 Global Anti corrosion Coating Market
10.2.2 Global Anti corrosion Coating Market by Region
10.3 Others
10.3.1 Global Others Market
10.3.2 Global Others Market by Region
Chapter 11. Qualitative Analysis (Subject to Data Availability)
11.1 Market Drivers
11.2 Market Restraints
11.3 Market Trends
11.4 Market Opportunity
11.5 Technological Road Map (Subject to Data Availability)
11.6 Product Life Cycle (Subject to Data Availability)
11.7 Customer and Buyer Behavior Analysis
11.7.1 Digital Engagement, Customer Experience & Relationship Analysis
11.14.2 AI-Driven Transformation of Industry Value Chain
11.14.3 Evolution of Business Models & Revenue Streams
11.14.4 AI-Driven Product, Service & Innovation Transformation
11.14.5 Customer Behavior, AI Adoption & Future Market Evolution
Chapter 12. TOP 10 Country Analysis
12.1 Country 1
12.2 Country 2
12.3 Country 3
12.4 Country 4
12.5 Country 5
12.6 Country 6
12.7 Country 7
12.8 Country 8
12.9 Country 9
12.10 Country 10
Chapter 13. Research Findings
13.1 Key Takeaways
13.2 Analyst Point of View
13.3 Assumptions and Acronyms
Chapter 14. Research Methodology and Sources
14.1 Primary Data Collection
14.1.1 Steps for Primary Data Collection
14.1.1.1 Identification of KOL
14.1.2 Backward Integration
14.1.3 Forward Integration
14.1.4 How Primary Research Help Us
14.1.5 Modes of Primary Research
14.2 Secondary Research
14.2.1 How Secondary Research Help Us
14.2.2 Sources of Secondary Research
14.3 Data Validation
14.3.1 Data Triangulation
14.4 Data Representation
Athenaeum AI Dashboard
Research Framework · 70:30 Primary:Secondary
Our Proprietary Methodology
Cognitive Market Research and Consulting "The Full Truth" methodology — a rigorous triangulation process that combines primary research, secondary validation, and expert calibration. Implemented by Chidanand Bilagi and team for the Specialty Vinyl Ester Resin Market Analysis Market analysis.
01
Primary Intelligence Gathering
Direct interviews with 50+ industry stakeholders including manufacturers, distributors, end-users, and regulatory bodies across all six regions.
02
Secondary Data Triangulation
Cross-referencing against trade databases, customs records, financial filings, patent databases, and verified industry publications.
03
Expert Validation Protocol
Each data point undergoes validation by minimum two independent domain experts with 15+ years of industry experience.
04
Athenaeum AI Processing
Our proprietary AI platform aggregates, normalizes, and identifies patterns across 10,000+ data points to surface non-obvious insights.
05
Editorial & QA Review
Final review by senior analysts ensures accuracy, coherence, and actionability of all insights and recommendations.
To maintain the integrity of our proprietary methodology and protect our elite expert network, specific source disclosures are reserved for full-access partners. Our research framework is anchored by a 70:30 primary-to-secondary ratio, ensuring your strategy is driven by real-time market intelligence rather than recycled, publicly available, or AI-generated data. Every deliverable includes an exhaustive source directory and grants direct analyst access.
Latest Articles about Specialty Vinyl Ester Resin Market
Specialty vinyl ester resin is a type of thermosetting polymer resin made by reacting epoxy resin with methacrylic acid. It has properties that make it useful for specific applications. Vinyl ester resins find extensive applications in FGD processes, particularly in limestone slurry piping and stack liners.
The Three Pillars of End-to-End Market Research Services
We don't just hand over data. We partner with your team across three integrated service lines — each designed to give you decision-grade intelligence on the Specialty Vinyl Ester Resin Market Analysis market.
Service 01
Market Survey
B2BB2C
Structured primary research across both B2B and B2C channels. We design and execute custom surveys targeting manufacturers, distributors, procurement heads, and end-consumers in the specialty vinyl ester resin market analysis ecosystem — validated by our global panel of 10,000+ industrial respondents.
What's Included
Buyer intent & sentiment analysis
Purchase cycle mapping
Price sensitivity research
Channel preference profiling
Competitive perception study
Most Requested
Service 02
Customized Market Data & Reports
CustomReady Report
Choose from our ready-to-access 8th Edition report or commission a fully customized dataset tailored to your exact strategic questions. Cross-splits, custom geographies, proprietary segmentation — we build the intelligence asset your board actually needs.
What's Included
Ready syndicate report
Custom data scope & segmentation
Excel quantitative models
Board-ready PPT with key findings
Secure cloud portal access
Service 03
Strategic Consultation
With SurveyWith Report
Every survey and every report comes with dedicated analyst consultation. Our senior research team walks your leadership through findings, answers strategic questions in real-time, and helps translate data into your next board presentation or investment thesis.
What's Included
Dedicated analyst assigned to you
Live walkthrough of findings
Strategic Q&A sessions
Go-to-market recommendations
NDA-protected engagement
Specialty Vinyl Ester Resin Market Related Reports
Tell us the specific segments, regions, or companies you need — and we will tailor the deliverable to your requirements.
Why Trust Us
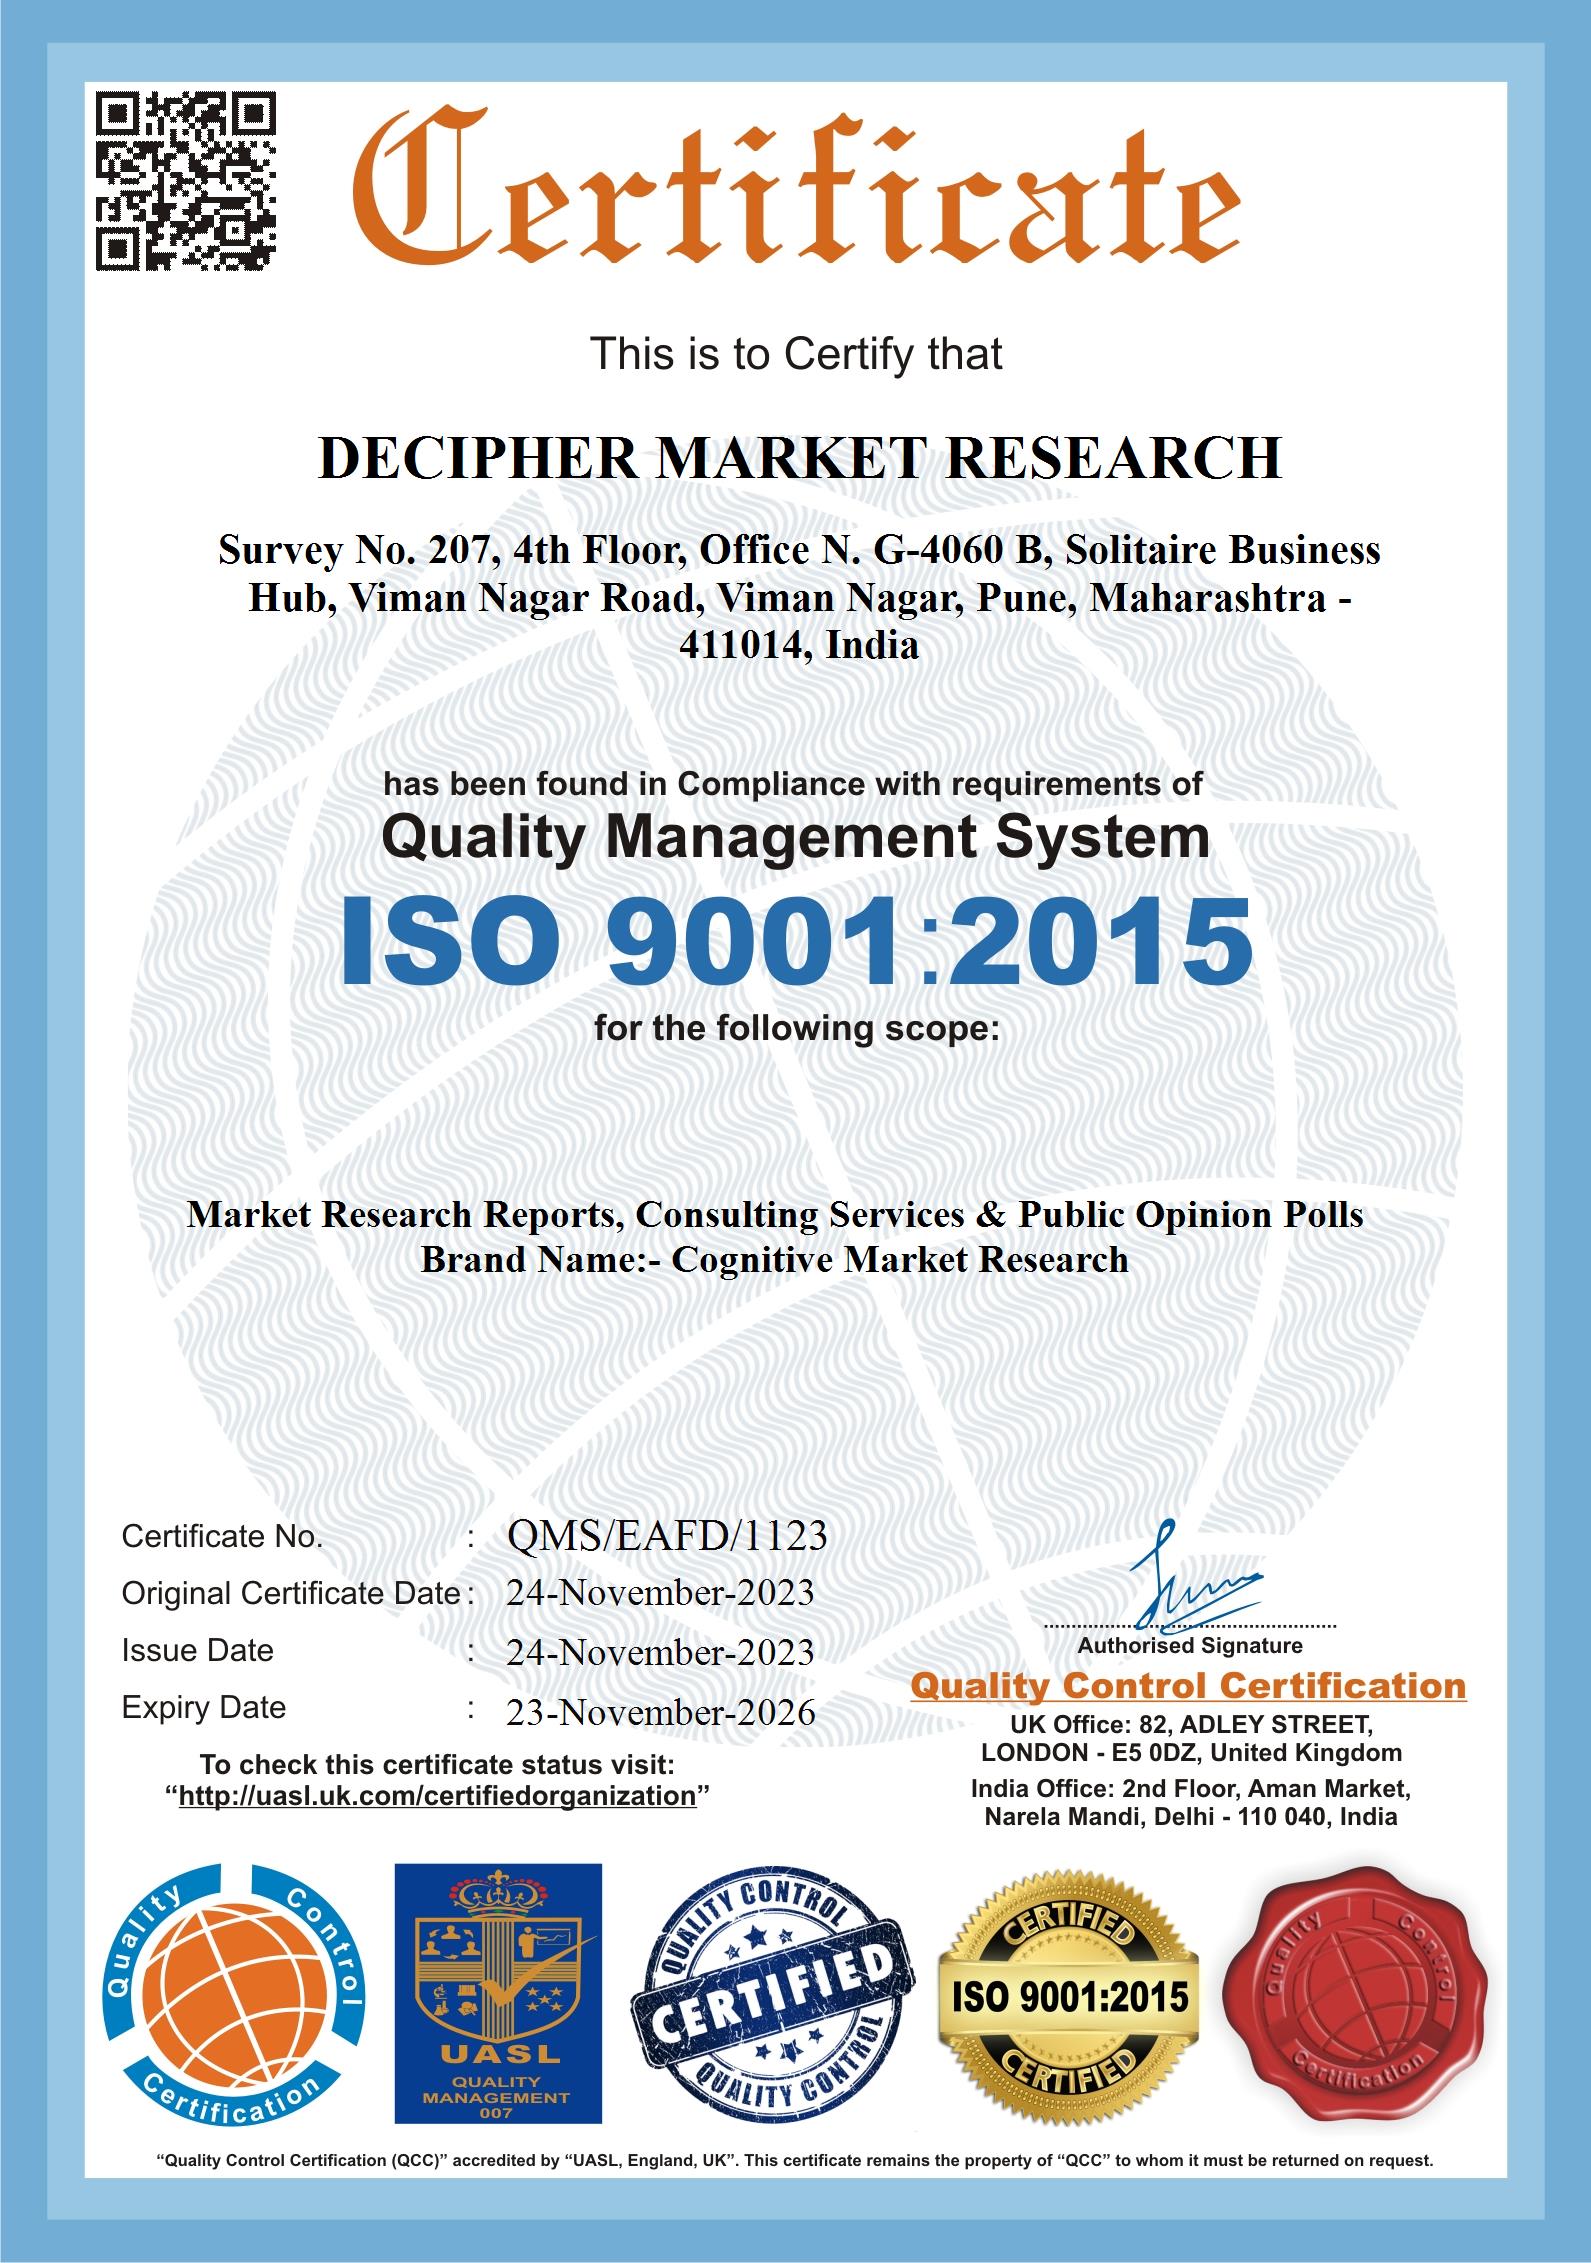
What these certifications mean to usA market figure is only as reliable as the system that produced it. That is why our accreditations cover the whole chain, not just the research step. ESOMAR and MRSI membership binds us to the professional codes that govern how respondents are recruited and how findings may be represented. ISO 20252 governs the research process itself; ISO 9001 and our quality control certification govern how consistently we repeat it. ISO 27001 and ISO 27701, alongside our GDPR, CCPA and DPDP compliance, govern what happens to your brief and your data once it reaches us; because a confidential scope is often more sensitive than the deliverable. ISO 14001, our D-U-N-S registration, Chamber of Commerce membership and DMCA protection speak to how the company itself is run and how its work is safeguarded.Our Clutch and Trustpilot profiles are deliberately listed next to them. They are the only signals on this page we do not issue ourselves, and they are the ones we would check first if we were you.
The global specialty vinyl ester resin market is on a solid growth trajectory with a 6.5% CAGR, driven by its superior performance in corrosion-resistant applications.
Asia Pacific is the undisputed market leader, accounting for over a third of the global market, with China and India being the primary growth engines due to massive industrial and infrastructure development.
Sustainability is a key influencing trend, with significant R&D efforts focused on developing bio-based, low-styrene, and recyclable resin systems to meet stricter environmental regulations and market demands.
While industrial applications like chemical processing and water treatment remain the bedrock of demand, high-growth opportunities are emerging in the renewable energy sector, particularly for manufacturing wind turbine blades.