We value your privacy
We use cookies to improve your experience and analyze traffic. By continuing, you consent to our use of cookies under GDPR, CCPA and other applicable laws. Privacy Policy
Cookie preferences
Choose which categories of cookies you allow. Strictly necessary cookies are always on.
Strictly necessary
Required for core site functionality, security and your session. Always active.
Analytics
Help us understand how visitors use the site (e.g. Google Analytics) so we can improve it.
Marketing
Used to measure campaigns and show you relevant ads on other sites (e.g. LinkedIn, Google Ads).
Green Hydrogen Market Analysis size 2021 was recorded $3060 Million whereas by the end of 2026 it will reach $13038.57 Million. According to the author, by 2033 Green Hydrogen market size will become $99090 Million. Green Hydrogen market will be growing at a CAGR of 33.6% during 2026 to 2033. Download a free sample with data verified by Kalyani Raje
Green Hydrogen Market Analysis from 2022 to 2034 Containing Market Size, Share along with its CAGR, Forecast and Trends
Top Countries — Revenue
Million
Access the full forecast model.
Country-level data · Company profiles · Editable dataset · Analyst consultation included.
Green Hydrogen Market Analysis — Presence
Geographical Analysis
Click countries to explore
Loading map…
Regional and Country Analysis
Global Green Hydrogen Market Analysis 2026
Country-level values are locked in this preview.
Request a free sample
to unlock the full breakdown.
Region / Country
2021 (A)
2025 (A)
2033 (P)
CAGR
Global
$ 3064.49 Million
$ 9763 Million
$ 99091.2 Million
33.6%
North America
$ 634.35 Million
$ 2030.7 Million
$ 20908.2 Million
33.839%
United States
$ 431.99 Million
$ 1360.57 Million
$ 13527.6 Million
33.256%
Canada
$ 119.89 Million
$ 393.96 Million
$ 4265.28 Million
34.683%
Mexico
$ 82.47 Million
$ 276.18 Million
$ 3115.33 Million
35.375%
Europe
$ 720.15 Million
$ 2245.49 Million
$ 21800.1 Million
32.86%
United Kingdom
$ 115.23 Million
$ 350.3 Million
$ 3204.61 Million
31.876%
France
$ 100.82 Million
$ 300.9 Million
$ 2681.41 Million
31.445%
Germany
$ 166.36 Million
$ 509.73 Million
$ 4796.01 Million
32.341%
Italy
$ 65.53 Million
$ 197.6 Million
$ 1765.81 Million
31.49%
Russia
$ 37.45 Million
$ 107.78 Million
$ 926.5 Million
30.854%
Spain
$ 46.81 Million
$ 150.45 Million
$ 1526 Million
33.589%
Sweden
$ 33.13 Million
$ 101.05 Million
$ 915.6 Million
31.719%
Denmark
$ 36.73 Million
$ 119.01 Million
$ 1264.4 Million
34.365%
Switzerland
$ 22.33 Million
$ 71.86 Million
$ 719.4 Million
33.372%
Luxembourg
$ 10.8 Million
$ 31.44 Million
$ 239.8 Million
28.914%
Rest of Europe
$ 84.98 Million
$ 305.39 Million
$ 3760.51 Million
36.867%
Asia Pacific
$ 1253.37 Million
$ 4090.7 Million
$ 43501 Million
34.381%
China
$ 512.63 Million
$ 1693.55 Million
$ 18357.4 Million
34.703%
Japan
$ 171.71 Million
$ 539.97 Million
$ 5350.63 Million
33.2%
South Korea
$ 97.76 Million
$ 306.8 Million
$ 3001.57 Million
32.988%
India
$ 209.31 Million
$ 695.42 Million
$ 7699.68 Million
35.06%
Australia
$ 45.12 Million
$ 137.04 Million
$ 1261.53 Million
31.98%
Singapore
$ 27.57 Million
$ 81.81 Million
$ 783.02 Million
32.623%
Taiwan
$ 51.39 Million
$ 159.54 Million
$ 1609.54 Million
33.5%
South East Asia
$ 101.52 Million
$ 343.62 Million
$ 3915.09 Million
35.545%
Rest of APAC
$ 36.35 Million
$ 132.95 Million
$ 1522.54 Million
35.632%
South America
$ 217.58 Million
$ 644.36 Million
$ 5747.29 Million
31.459%
Brazil
$ 91.38 Million
$ 266.12 Million
$ 2287.42 Million
30.853%
Argentina
$ 38.73 Million
$ 115.34 Million
$ 1040.26 Million
31.642%
Colombia
$ 29.37 Million
$ 91.5 Million
$ 902.32 Million
33.12%
Peru
$ 14.36 Million
$ 44.46 Million
$ 425.3 Million
32.614%
Chile
$ 19.58 Million
$ 57.99 Million
$ 511.51 Million
31.276%
Rest of South America
$ 24.15 Million
$ 68.95 Million
$ 580.48 Million
30.515%
Middle East
$ 159.35 Million
$ 488.15 Million
$ 4657.29 Million
32.571%
Saudi Arabia
$ 66.77 Million
$ 201.61 Million
$ 1858.26 Million
32%
Turkey
$ 30.12 Million
$ 94.21 Million
$ 936.11 Million
33.245%
UAE
$ 21.04 Million
$ 64.44 Million
$ 610.1 Million
32.445%
Egypt
$ 19.44 Million
$ 58.09 Million
$ 521.62 Million
31.57%
Qatar
$ 9.4 Million
$ 30.75 Million
$ 335.33 Million
34.802%
Rest of Middle East
$ 12.59 Million
$ 39.05 Million
$ 395.87 Million
33.579%
Africa
$ 79.68 Million
$ 263.6 Million
$ 2477.28 Million
32.321%
East Africa
xxxx
xxxx
xxxx
xxxx
West Africa
xxxx
xxxx
xxxx
xxxx
North Africa
xxxx
xxxx
xxxx
xxxx
South Africa
$ 34.18 Million
$ 114.4 Million
$ 1099.91 Million
32.698%
The global green hydrogen market is undergoing a profound transformation, moving from a niche, technologically-driven sector to a mainstream component of the global energy transition. This shift is fueled by a confluence of factors, including escalating climate change concerns, national net-zero commitments, and the pursuit of energy independence. Green hydrogen, produced via electrolysis powered by renewable sources, offers a versatile and zero-emission energy carrier capable of decarbonizing a wide array of applications, from industrial feedstocks to long-haul transport and energy storage. As technology matures and economies of scale are realized, the market is set to unlock significant economic and environmental benefits.
Global Green Hydrogen Market Drivers
Stringent Decarbonization Policies and Net-Zero Pledges: Governments worldwide are implementing legally binding targets to reduce greenhouse gas emissions. Policies such as carbon pricing, emissions trading systems, and direct subsidies for clean technologies make green hydrogen an increasingly attractive and necessary solution for industries to comply with regulations and achieve climate goals.
Decreasing Cost of Renewable Energy: The continuous and rapid decline in the Levelized Cost of Energy (LCOE) from solar photovoltaics and wind turbines is the most significant driver for green hydrogen. Since electricity is the primary cost component in electrolysis, cheaper renewable power directly translates into more competitive green hydrogen production costs.
Advancements in Electrolyzer Technology: Ongoing research and development are leading to more efficient, durable, and cost-effective electrolyzer technologies (Alkaline, PEM, and Solid Oxide). Industrial-scale manufacturing and automation are further driving down capital costs, making large-scale green hydrogen projects more financially viable.
Global Green Hydrogen Market Trends
Development of Hydrogen Hubs and Valleys: A key trend is the creation of integrated regional ecosystems where green hydrogen production, storage, and consumption are co-located. These hubs foster collaboration between industries, optimize infrastructure use, and create economies of scale, accelerating market development.
Focus on Green Hydrogen Derivatives for Export: In regions with abundant renewable resources, there is a growing trend to produce green hydrogen derivatives like green ammonia and methanol. These molecules are easier and more cost-effective to store and transport over long distances, enabling the creation of a global hydrogen trade market.
Sector Coupling and Integration: Green hydrogen is increasingly seen as a critical enabler of sector coupling, linking the power sector with end-use sectors like transportation (fuel cell vehicles), industry (steel and chemical production), and buildings (heating). This integration enhances the flexibility and resilience of the entire energy system.
Global Green Hydrogen Market Restraints
High Production Costs Compared to Grey Hydrogen: Despite cost reductions, green hydrogen is currently still two to three times more expensive than grey hydrogen produced from natural gas. This price disparity remains a major barrier to widespread adoption, particularly in the absence of strong carbon pricing or subsidies.
Lack of Dedicated Infrastructure: The absence of a well-developed infrastructure for the transportation (pipelines, tankers) and storage (geological storage, liquid or compressed tanks) of hydrogen on a large scale presents a significant logistical and financial bottleneck. Building this infrastructure requires massive, coordinated investment.
Water Scarcity and Electrolysis Requirements: The electrolysis process requires substantial amounts of purified water. In many of the world's sunniest and windiest regions, which are ideal for renewable energy production, water is a scarce and valuable resource, creating a potential conflict and constraint on large-scale green hydrogen production.
Market Size: $634.348 Million (2021) -> $2030.7 Million (2025) -> $20908.2 Million (2033)
CAGR (2021-2033): 33.839%
Country-Specific Insight: The U.S. is the regional powerhouse, poised to hold 13.9% of the global green hydrogen market by 2025, driven by massive federal incentives. Canada is a significant player with a projected 4.0% global share, leveraging its abundant hydropower. Mexico shows strong growth potential, accounting for an estimated 2.8% of the global market in 2025, benefiting from its excellent solar resources.
Regional Dynamics:
Key Drivers
The U.S. Inflation Reduction Act (IRA) provides a powerful production tax credit (45V) that can make green hydrogen cost-competitive with grey hydrogen.
Canada's Clean Hydrogen Investment Tax Credit and abundant low-cost renewable energy, especially hydropower.
Development of regional Hydrogen Hubs funded by the Department of Energy to accelerate infrastructure and create demand centers.
Key Trends
A focus on decarbonizing heavy-duty transportation, including long-haul trucking and logistics.
Integration of green hydrogen production with existing industrial corridors, particularly along the Gulf Coast.
Growing interest in using green hydrogen for long-duration energy storage to support a grid with high renewable penetration.
Key Restraints
Complex and lengthy permitting processes for new renewable energy projects and hydrogen infrastructure.
Competition from established natural gas infrastructure and low-cost blue hydrogen projects.
Interstate regulatory challenges for building new hydrogen pipelines.
Technology Focus
The region sees a dual focus on both Proton Exchange Membrane (PEM) electrolyzers, favored for their flexibility in pairing with variable renewables like solar and wind, and larger-scale Alkaline electrolyzers for projects with consistent power sources like hydropower. There is also significant R&D into next-generation technologies to further reduce costs and improve efficiency.
Market Size: $720.154 Million (2021) -> $2245.49 Million (2025) -> $21800.1 Million (2033)
CAGR (2021-2033): 32.86%
Country-Specific Insight: Europe is a leading market, collectively accounting for 23.0% of the global share in 2025. Germany is at the forefront, holding 5.2% of the global market, with the UK (3.6%), France (3.1%), Spain (1.5%), and Denmark (1.2%) also being major contributors. The collective efforts, including initiatives in Italy (2.0%), Sweden (1.0%), and others, underscore a continent-wide push.
Regional Dynamics:
Key Drivers
The ambitious REPowerEU plan and Green Deal, which set aggressive targets for domestic production and imports of renewable hydrogen.
Strong carbon pricing through the EU Emissions Trading System (ETS), which incentivizes industries to switch to cleaner alternatives.
Substantial public funding mechanisms like the European Hydrogen Bank and Important Projects of Common European Interest (IPCEI).
Key Trends
Development of a "European Hydrogen Backbone," a plan to create a continental network of hydrogen pipelines by repurposing existing gas grids and building new ones.
Establishment of international partnerships with regions like Africa and the Middle East to secure future hydrogen imports.
Strong focus on decarbonizing heavy industries like steel, chemicals, and refining.
Key Restraints
High electricity prices in many parts of Europe, which directly impacts the cost of green hydrogen production.
Heavy reliance on energy imports, creating geopolitical vulnerabilities for hydrogen supply chains.
Regulatory fragmentation across member states, which can slow down cross-border projects and market integration.
Technology Focus
Europe is a technology leader, with a strong focus on advanced PEM electrolyzer technology due to its suitability for the continent's large offshore wind capacity. There is also significant investment in next-generation Solid Oxide electrolyzers, which promise higher efficiencies, particularly when integrated with industrial heat sources.
Market Size: $1253.37 Million (2021) -> $4090.7 Million (2025) -> $43501 Million (2033)
CAGR (2021-2033): 34.381%
Country-Specific Insight: APAC is the largest global market, projected to hold a commanding 41.9% global share by 2025. China is the undisputed leader, accounting for 17.3% of the global market. India is rapidly emerging with a 7.1% global share, followed by Japan (5.5%), South Korea (3.1%), and Australia (1.4%), all making significant investments.
Regional Dynamics:
Key Drivers
Energy security concerns and a desire to reduce reliance on imported fossil fuels in countries like China, India, and Japan.
Government-led national hydrogen missions, such as India's National Green Hydrogen Mission, which provide strong policy and financial support.
The region's massive manufacturing capabilities, which are being leveraged to produce electrolyzers and other hydrogen equipment at scale.
Key Trends
Development of large-scale, export-oriented green hydrogen and ammonia projects, particularly in Australia, leveraging vast solar and wind resources.
Focus on deploying hydrogen fuel cell vehicles, with South Korea and Japan leading in mobility applications.
China's strategy to use green hydrogen to decarbonize its vast industrial and chemical sectors.
Key Restraints
Significant water stress in key production areas, posing a challenge for electrolysis.
A diverse and complex regulatory landscape across different countries, which can complicate regional trade and investment.
Grid infrastructure in some developing parts of the region is not yet robust enough to support large-scale renewable energy integration.
Technology Focus
The region benefits from a diverse technology approach. Cost-effective and mature Alkaline electrolyzer technology dominates in China due to its focus on scale and cost reduction. However, PEM technology is gaining rapid traction in countries like Japan and South Korea for mobility applications and in Australia for export-oriented projects paired with variable renewables.
Market Size: $217.578 Million (2021) -> $644.358 Million (2025) -> $5747.29 Million (2033)
CAGR (2021-2033): 31.459%
Country-Specific Insight: South America is an emerging market with immense potential, holding about 6.6% of the global market in 2025. Brazil leads the region, accounting for 2.7% of the global market, thanks to its strong renewable grid. Argentina (1.2%), Colombia (0.9%), and Chile (0.6%) are also developing projects aimed at leveraging their natural resources for export.
Regional Dynamics:
Key Drivers
Exceptional renewable energy resources, including vast hydropower in Brazil and Colombia and some of the world's best solar and wind resources in Chile and Argentina.
Strong potential to become a major exporter of green hydrogen and its derivatives (especially green ammonia) to markets in Europe and Asia.
Proactive government strategies and frameworks to attract foreign investment for large-scale export projects.
Key Trends
A primary focus on developing large, export-oriented hubs, particularly in coastal regions with good port access.
Formation of international consortiums to develop mega-projects that combine renewable generation, electrolysis, and ammonia synthesis.
Growing interest in using green hydrogen for domestic applications, such as decarbonizing mining operations and producing green fertilizers.
Key Restraints
Political and economic instability in some countries can deter long-term, capital-intensive investments.
Lack of domestic industrial demand to anchor initial projects, making them heavily reliant on securing international off-take agreements.
Infrastructure deficits, including port capacity and grid connectivity, in potential project locations.
Technology Focus
The technology focus is on proven and scalable solutions. Both Alkaline and PEM electrolyzers are being deployed, with the choice often depending on the specific project's power source. For projects powered by the region's abundant hydropower, large-scale Alkaline systems are cost-effective, while projects using new solar and wind farms often favor the flexibility of PEM technology.
Market Size: $159.353 Million (2021) -> $488.15 Million (2025) -> $4657.29 Million (2033)
CAGR (2021-2033): 32.571%
Country-Specific Insight: The Middle East is positioning itself as a future clean energy powerhouse, representing 5.0% of the global market in 2025. Saudi Arabia leads this charge, holding a 2.1% global share with its mega-projects. Turkey (1.0%), the UAE (0.7%), and Egypt (0.6%) are also making significant strides to leverage their solar resources and strategic location.
Regional Dynamics:
Key Drivers
Strategic vision to diversify economies away from oil and gas and become leaders in the future energy market.
Extremely high solar irradiance, providing some of the lowest-cost solar power in the world, which is a key advantage for green hydrogen production.
Availability of capital and state-backed support for ambitious, large-scale energy projects.
Key Trends
Development of giga-scale integrated projects, such as NEOM in Saudi Arabia, which combine massive renewable generation with hydrogen and ammonia production for export.
Leveraging existing expertise in handling and exporting energy molecules (like LNG) to build a green hydrogen export business.
Strategic location between European and Asian markets, positioning the region as a key global hydrogen trading hub.
Key Restraints
Extreme water scarcity across the region necessitates coupling hydrogen production with large-scale, energy-intensive desalination plants, adding complexity and cost.
High ambient temperatures can reduce the efficiency of electrolyzers and other equipment.
Geopolitical tensions in the region can introduce risks for long-term investments and supply chain stability.
Technology Focus
The focus in the Middle East is on massive, world-scale projects. This favors mature, large-scale Alkaline electrolyzer technology, which can be deployed in the gigawatt range. Integration with advanced desalination technologies is a critical area of focus, as is the optimization of cooling systems to maintain electrolyzer performance in hot climates.
Market Size: $79.677 Million (2021) -> $263.601 Million (2025) -> $2477.28 Million (2033)
CAGR (2021-2033): 32.321%
Country-Specific Insight: Africa is a nascent but high-potential market, accounting for 2.7% of the global share in 2025. South Africa (1.2% global share) and Nigeria (0.8% global share) are key early movers, alongside countries like Namibia and Morocco that are planning large export-oriented projects. The continent's vast renewable potential is its greatest asset.
Regional Dynamics:
Key Drivers
Arguably the world's best co-located solar and wind resources, particularly in North and Southern Africa, offering immense potential for low-cost renewable power.
Proximity to Europe, making North African countries prime candidates to supply the EU market via pipelines or shipping.
Potential for green hydrogen to leapfrog traditional energy infrastructure development and provide clean energy for local industrialization and power generation.
Key Trends
A strong focus on developing projects geared towards exporting green hydrogen and ammonia to Europe.
Bilateral agreements and partnerships being formed between African and European nations to finance and develop projects.
Growing recognition of using green hydrogen to produce fertilizers locally, addressing food security challenges.
Key Restraints
Significant lack of existing infrastructure, including grids, roads, and ports, which increases project development costs and timelines.
Limited access to financing and high perceived investment risk in many parts of the continent.
Political instability and challenging regulatory environments can be major barriers for securing the long-term investments required.
Technology Focus
The technology approach is tailored to the environment. Robust, cost-effective, and easy-to-maintain electrolyzer technologies, such as containerized Alkaline and PEM systems, are favored. There is a strong focus on developing off-grid projects that are not reliant on unstable national grids, and on solutions that are resilient to challenging environmental conditions like dust and heat.
A = Actual · E = Estimated · P = Projected · 🔒 Locked values require full access. Click headers to sort.
Alkaline Water Electrolyser Technology is projected to garner significant market share:
- Alkaline Water Electrolyser was the largest segment with 69.68% share of total revenue generated in 2022.
AWE is the most matured green hydrogen technology among all the other technologies. This can be attributed further due to relatively low cost per kW of installed capacity. The reduction in price has primarily achieved due to high usage of AWE by various manufacturers. Recent development in AWE technology results in hydrogen delivery upto 30 barg, with even minimum load. Moreover, few companies are also assessing measures to reduce electrical intermittency to enhance operation of AWE, projecting its significant growth in near future.
Proton exchange membrane electrolyzer Green Hydrogen Market Analysis
Alkaline electrolyzer Green Hydrogen Market Analysis
XX
Alkaline electrolyzer Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Solid oxide electrolyzer Green Hydrogen Market Analysis
XX
Solid oxide electrolyzer Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Market size by (Illustrative, 2025)
Share distribution (2025)
Disclaimer: The charts and graphs are for illustrative purposes only and do not represent actual market values. To access accurate quantitative data, please request a paid report or request free sample.
To learn more about market share and segmentation, request the free sample pages.
Competitor Analysis
Recent Developments:
January 2021
Siemens Gamesa and Siemens Energy has unlocked a new era of offshore green hydrogen production:
In order to reach 2015 Paris Agreement Goal, both the companies have announced to join forces combining their ongoing wind-to-hydrogen developments to address one of the major challenges: decarbonizing the economy to solve the climate crisis.
June 2022
Plug Power Inc. has built large scale green hydrogen generation plant in Europe:
Plug Power Inc. has announced to build a 35-tons-per-day green hydrogen generation plant at Port of Antwerp-Bruges in the heart of Europe. The company has also signed a 30-year concession agreement to build the plant at the Belgian port, the second largest in Europe.
November 2021
Heliogen, Inc. and Bloom Energy Corporation has partnered to produce low-cost green hydrogen:
Heliogen, Inc. and Bloom Energy Corporation has announced the generation of green hydrogen by integrating the companies’ technologies – Heliogen’s concentrated solar energy system and the Bloom Electrolyzer. The successful demonstration in Lancaster, California produced hydrogen and showcased the many benefits of combining the companies’ complementary technologies to achieve low-cost green hydrogen production.
September 2022
Linde has decided to increase green hydrogen production in the U.S.
Linde has announced that it will build a 35-megawatt PEM (Proton Exchange Membrane) electrolyzer to produce green hydrogen in Niagara Falls, New York. The new plant will be the largest electrolyzer installed by Linde globally and will more than double Linde’s green liquid hydrogen production capacity in the United States.
June 2022
Air Liquide and Siemens Energy formed a joint venture for the European production of large-scale renewable hydrogen electrolyzers. This will enable the emergence of a sustainable hydrogen economy in Europe and foster a European ecosystem for electrolysis and hydrogen technology. Production is expected to begin in the second half of 2023 and ramp-up to an annual production capacity of three gigawatts by 2025.
Click any bar or cell to request the full company profile
Top Companies (In no particular order)
2022 (A)
2023 (A)
2024 (A)
2025 (A)
SGH2 Energy
•••
•••
•••
•••
Air Liquide
•••
•••
•••
•••
FuelCellsWorks
•••
•••
•••
•••
Siemens Gas and Power
•••
•••
•••
•••
Linde
•••
•••
•••
•••
ENGIE
•••
•••
•••
•••
Nel ASA
•••
•••
•••
•••
Hydrogenics
•••
•••
•••
•••
Uniper SE
•••
•••
•••
•••
Air Products and Chemicals
•••
•••
•••
•••
Toshiba Energy Systems and Solutions Corporation
•••
•••
•••
•••
Green Hydrogen Systems
•••
•••
•••
•••
We Provide Regional Breakdown of this Companies and Company specific to any Country, Region, Product/ service as well. We cover market share analysis for publicly listed companies as well as privately held companies, subject to data availability.
The global green hydrogen market is poised for exponential growth, surging from approximately $3.06 billion in 2021 to an estimated $99.09 billion by 2033, demonstrating a remarkable compound annual growth rate (CAGR) of 33.6%. This rapid expansion is fundamentally driven by the global imperative to decarbonize hard-to-abate sectors such as heavy industry and transportation. Supportive government policies, including substantial subsidies and ambitious national hydrogen strategies, are creating a fertile ground for investment. Concurrently, the declining costs of renewable energy, particularly solar and wind, are making the electrolysis process for producing green hydrogen increasingly economically viable. The market is transitioning from pilot projects to large-scale, commercial operations, cementing green hydrogen's role as a cornerstone of the future clean energy ecosystem. However, challenges related to production costs, infrastructure development, and water usage persist.
Key strategic insights from our comprehensive analysis reveal:
The market is characterized by hyper-growth, with projections indicating a more than 30-fold increase in market value between 2021 and 2033, underscoring the massive investment and policy momentum behind the technology.
Asia Pacific currently leads the market, driven by significant government initiatives and industrial demand in countries like China and India. Europe and North America follow closely, propelled by strong regulatory frameworks such as the REPowerEU plan and the U.S. Inflation Reduction Act.
While the long-term outlook is exceptionally strong, the primary hurdles remain the high initial production cost compared to fossil-fuel-based hydrogen and the significant capital investment required for building out a comprehensive transportation and storage infrastructure.
Strategic Recommendations for Manufacturers
Manufacturers in the green hydrogen space should prioritize a multi-pronged strategy. Firstly, focus relentlessly on scaling up electrolyzer production capacity to drive down capital costs through economies of scale and automation. Secondly, invest heavily in research and development to improve electrolyzer efficiency, durability, and performance, thereby reducing the overall levelized cost of hydrogen. Thirdly, form strategic alliances with renewable energy developers, EPC contractors, and industrial off-takers to de-risk projects and secure long-term revenue streams. Finally, embrace modular designs and standardization to reduce project lead times and construction costs, enabling faster deployment to meet soaring demand.
Hydrogen is the lightest element in the universe and is abundantly available. However, 96% of this hydrogen comes from fossil fuels and remaining 4% can be produced by electrolysis. Green hydrogen is any hydrogen that is produced from renewable energy. This method uses an electrical current to separate the hydrogen from the oxygen in water.
Green hydrogen, which is sourced from renewable energy, does not emit carbon dioxide into the atmosphere. Thus, consistent use of green hydrogen would save 830 million tonnes of CO2 that are emitted annually when this gas is produced using fossil fuels.
Use of hydrogen as a fuel is currently a reality in countries like the United States, Russia, China, France and Germany. Others like Japan are going even further and aspire to become a hydrogen economy followed by India.
Analyst Conclusion
As per Cognitive's Research Analyst, Green Hydrogen are produced via electrolysis powered by renewable sources, offering a versatile and zero-emission energy carrier. They play an essential role in decarbonizing a wide array of applications, from industrial feedstocks to long-haul transport and energy storage.
Looking at the Historical Growth The global market expanded from $3060 Million in 2021 to an estimated $13038.57 Million in 2026 due to escalating climate change concerns, national net-zero commitments, and the pursuit of energy independence. Regionally, Asia Pacific grew from $1253.37 Million in 2021 to $5496.07 Million in 2026, while Europe progressed from $720.154 Million to $2976.22 Million over the same period.
Currently in 2026, Asia Pacific holds a commanding 42.15% of the global market, driven by energy security concerns and robust government-led national hydrogen missions. The hard-to-abate industrial sectors segment remains the primary consumer of Green Hydrogen. This region is also set to remain the fastest-growing market, exhibiting the highest CAGR of 34.381%, fueled by proactive government support and significant industrial demand across major economies like China and India.
The market is witnessing a definitive shift towards the development of Hydrogen Hubs and Valleys, driven by initiatives to foster collaboration between industries, optimize infrastructure use, and create economies of scale. Ongoing innovation in electrolyzer technology is also leading, focusing on improving efficiency, durability, and performance.
In the future, The global Green Hydrogen market will reach to $99090 Million by 2033, expanding at a compound annual growth rate of 33.6% from 2021, primarily driven by stringent global decarbonization policies and declining renewable energy costs. Ongoing innovation in electrolyzer technology and the strong trend towards global hydrogen trade markets will also contribute significantly.
Senior Research Analyst at Cognitive Market Research
Kalyani Raje is a distinguished research leader and the Co-Founder & Chief Research Officer at Cognitive Market Research and Consulting, a global market research and consulting firm specializing in data-driven intelligence and strategic business insights. With over a decade of experience in market research, competitive intelligence, and analytical consulting, she has played a pivotal role in helping organizations understand evolving market landscapes and make informed strategic decisions across industries including FMCG, IT, Telecom, Automotive, Electronics, Healthcare, and Consumer Goods.
As a research professional, Kalyani is recognized for her expertise in developing rigorous research methodologies, interpreting complex market data, and transforming insights into actionable business strategies. Her analytical approach, combined with a strong understanding of global industry trends and consumer behavior, has enabled enterprises, manufacturers, investors, and business leaders to navigate competitive environments with greater confidence and clarity.
Kalyani is an active member of ESOMAR and the Market Research Society of India (MRSI), reflecting her commitment to maintaining ethical, transparent, and internationally recognized research standards. She strongly advocates adherence to the ICC/ESOMAR International Code on Market and Social Research, reinforcing her dedication to research integrity, data quality, and responsible business practices within the global insights industry.
In 2026, Kalyani was invited as a Speaker at ESOMAR Africa 2026, where she shared her expertise on Africa’s Youthquake: Decoding the Continent’s Largest Generation and Its Transformative Impact. Her participation highlighted her thought leadership in understanding demographic shifts, emerging markets, and the evolving role of data and analytics in shaping future business opportunities.
Throughout her professional journey, Kalyani has been instrumental in driving research excellence, mentoring analytical teams, and building scalable research frameworks that deliver high-value intelligence to global clients. Her passion for innovation, strategic thinking, and evidence-based decision-making continues to strengthen Cognitive Market Research’s position as a trusted global insights partner for businesses worldwide.
What you get, what it costs, and how we stand behind it
Every licence includes two years of analyst access, not just a document. Below: the decisions this research supports, what is included, what is charged separately, and the checks every figure passes before release.
Data updatedSeptember 20268th Edition · Delivery in 5–7 business days
What our consultation helps you decide
If you are deciding…
Whether to enter or expand in a market
Where to invest across the portfolio
Which customer groups to target
Where to direct product development
How to position against competitors
How your performance compares to the market
Whether to acquire, partner or divest
Whether to invest or fund
How to plan budgets and targets
Which route to market to build
How to assess supply and sourcing risk
These are the decisions clients bring us most often — but they are not the limit. Most engagements surface questions the data alone does not answer, and that is where the consultation does the work. Tell us what you are deciding, and our analyst will tell you what the research can support.
Included in your purchase
A licence is a two-year relationship, not a one-time download. Everything below is included at no additional cost.
Access & formats
Multi-format delivery
Cloud/HTML with master and team access, PDF, Excel data models, board-ready PPT, and the Athenaeum AI consultant.
Interactive dashboard
Toggle the dataset across global currencies and languages in real time.
Portfolio-level insight
Three-year country-level market sizing across your entire product range, not a single line.
Updates & editions
8 quarterly refreshes
Complimentary data updates every quarter for two years, so your figures track the market rather than the publication date.
Next two annual editions
The following two yearly editions are added to your account automatically.
Dated at source
Every deliverable carries a visible “data updated” date so recency is never in question.
Advisory & support
6 hours analyst consultation
One-to-one time with the lead analyst for Q&A, walkthroughs, or to join an internal executive discussion as an independent adviser.
Two-year strategic advisory
Continuing support on assumptions, methodology and evolving requirements for the full licence period.
24/7 client support
Round-the-clock account support for ad-hoc queries and new requests.
How delivery works
From first enquiry to dispatch, with a named analyst attached at every stage. Standard delivery is 5–7 business days from scope confirmation.
Before you buy
Complimentary preview. The full data structure and table of contents, so you can judge scope before committing.
Scope tailored to your question. Share your use case and problem statement and we shape the research around it.
Modular purchasing. Buy specific chapters, sections or graphs at nominal rates without the full dataset.
Confidentiality from first contact
Your proprietary requirements and personal information are safeguarded under GDPR (EU/UK), CCPA (USA) and the DPDP Act (India).
All project parameters are bound by a non-disclosure agreement from your first enquiry — not from the point of purchase.
Delivery execution
01Scope confirmationReview the preview with your dedicated analyst to agree variables, structure and formats.
02Extraction & customisationWe isolate the precise segments and parameters you need from the core database.
03Current-market validationFigures are refreshed and cross-checked against current-quarter market conditions.
04Expert QASenior specialists run qualitative checks and resolve overlaps and discrepancies.
05Dispatch & walkthroughDelivered in 5–7 business days, followed by an analyst-led walkthrough and Q&A.
Scope, timeline and price are confirmed in writing before any work starts. Customised datasets follow the same validation method and quality review as the standard report.
Available at additional cost
Outside the standard licence, but available on request. Scope and price are confirmed in writing before any work begins.
Raw interview transcriptsVerbatim records from the primary research conducted for this study, released under NDA and priced separately.
Live primary surveyNew fieldwork designed to your question, run through our B2B and B2C panel. Delivered as a standalone market survey engagement.
Extended forecast horizonProjection beyond the published forecast period, built on the same model and validation method.
Custom scope and segmentationProduct definitions, countries, competitor sets, time horizon, and metrics such as volume, price trend, import/export or TAM/SAM/SOM.
Not available at any priceThe identities of the industry experts who contribute to and validate our research are protected under non-disclosure agreement. We will describe their roles, sectors and years of experience, and an expert can join your call as an independent third party — but we do not sell or disclose names.
How we assure quality
Before any dataset is released, it passes a five-stage review carried out by senior analysts and independent industry specialists.
Senior analyst reviewEvery headline figure — market size, forecast, growth rate — is checked by a senior analyst before publication.
Independent expert verificationEach data point is reviewed by at least two industry specialists with 15+ years in the category.
Arithmetic and reconciliationCountry and regional figures are reconciled to their totals and cross-checked against observable market conditions.
Divergence resolutionWhere sources conflict, we trace the cause rather than averaging it away, and record the basis for the figure we publish.
Dated releaseEach deliverable ships with an explicit data-updated date and the edition it belongs to.
By combining statistical validation with qualitative vetting by practitioners, we release figures that are structurally sound and ready to carry into a board paper, an investment memo or a regulatory filing.
Need something outside this scope? Share your use case and we will confirm feasibility, timeline and price in writing before work starts.
Frequently Asked Questions
Response: High need for achieving deep decarbonization is driving the growth of green hydrogen market across the globe
Response: Europe is dominating the Green Hydrogen market in year 2022.
Response: Study involved in-depth qualitative and quantitative analyses of the market. Moreover, research study involves the use of secondary sources and databases such as key companies’ annual reports, paid & public database, Bloomberg, and Factiva to identify and collect information useful for a technical and market-oriented study of the global green hydrogen market. market value evaluation is done by using top-down as well as bottom-up analysis.
Response: Yes, the report includes a COVID-19 impact analysis.
The report has been analyzed from year 2018 to 2030 in which
• 2018-2022: Historic Period
• 2022: Base Year
• 2023-2030: Forecast Period
★ Reviews
Rate this report
Green Hydrogen Market Analysis — Table of Contents
Disclaimer:
This is just a redacted sample pages of the actual deliverable report and only for representative purposes
Charts/Graphs/Numbers/data are only for Representative purposes and do not depict actual statistics.
The table of Contents differs according to the user License selection. Current Displayed TOC is for the Corporate User License Report Edition. TOC Customization options: Add or Remove section/s Or chapter/s from the report.
Specific Tables, Graphs, Sections, and Chapters can be ordered at a discounted price.
If applicable; On Request Volume Data will also be provided (at an Additional Cost).
SGH2 Energy, Air Liquide, FuelCellsWorks, Siemens Gas and Power, Linde, ENGIE, Nel ASA, Hydrogenics, Uniper SE, Air Products and Chemicals, Toshiba Energy Systems and Solutions Corporation, Green Hydrogen Systems
Chapter 1. Competitor Analysis (Subject to Data Availability (Private Players))
1.1 Top Competitors Analysis
1.1.1 Global Green Hydrogen Market Analysis by Key Players
1.1.2 Segment Market Analysis by Key Players
1.1.3 Top Players Ranking 2024
1.1.4 New Product Launch Analysis
1.1.5 Industry Mergers and Acquisition Analysis
1.2 Company Profile (Data Subject to Availability) Sample Format
1.2.1 SGH2 Energy
1.2.1.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.1.2 Business Overview
1.2.1.3 Financials (Subject to data availability)
1.2.1.4 R&D Investment (Subject to data availability)
1.2.1.5 Product Types Specification
1.2.1.6 Business Strategy
1.2.1.7 Recent Developments
1.2.1.8 Management Change
1.2.1.9 S.W.O.T Analysis
1.2.2 Air Liquide
1.2.2.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.2.2 Business Overview
1.2.2.3 Financials (Subject to data availability)
1.2.2.4 R&D Investment (Subject to data availability)
1.2.2.5 Product Types Specification
1.2.2.6 Business Strategy
1.2.2.7 Recent Developments
1.2.2.8 Management Change
1.2.2.9 S.W.O.T Analysis
1.2.3 FuelCellsWorks
1.2.3.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.3.2 Business Overview
1.2.3.3 Financials (Subject to data availability)
1.2.3.4 R&D Investment (Subject to data availability)
1.2.3.5 Product Types Specification
1.2.3.6 Business Strategy
1.2.3.7 Recent Developments
1.2.3.8 Management Change
1.2.3.9 S.W.O.T Analysis
1.2.4 Siemens Gas and Power
1.2.4.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.4.2 Business Overview
1.2.4.3 Financials (Subject to data availability)
1.2.4.4 R&D Investment (Subject to data availability)
1.2.4.5 Product Types Specification
1.2.4.6 Business Strategy
1.2.4.7 Recent Developments
1.2.4.8 Management Change
1.2.4.9 S.W.O.T Analysis
1.2.5 Linde
1.2.5.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.5.2 Business Overview
1.2.5.3 Financials (Subject to data availability)
1.2.5.4 R&D Investment (Subject to data availability)
1.2.5.5 Product Types Specification
1.2.5.6 Business Strategy
1.2.5.7 Recent Developments
1.2.5.8 Management Change
1.2.5.9 S.W.O.T Analysis
1.2.6 ENGIE
1.2.6.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.6.2 Business Overview
1.2.6.3 Financials (Subject to data availability)
1.2.6.4 R&D Investment (Subject to data availability)
1.2.6.5 Product Types Specification
1.2.6.6 Business Strategy
1.2.6.7 Recent Developments
1.2.6.8 Management Change
1.2.6.9 S.W.O.T Analysis
1.2.7 Nel ASA
1.2.7.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.7.2 Business Overview
1.2.7.3 Financials (Subject to data availability)
1.2.7.4 R&D Investment (Subject to data availability)
1.2.7.5 Product Types Specification
1.2.7.6 Business Strategy
1.2.7.7 Recent Developments
1.2.7.8 Management Change
1.2.7.9 S.W.O.T Analysis
1.2.8 Hydrogenics
1.2.8.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.8.2 Business Overview
1.2.8.3 Financials (Subject to data availability)
1.2.8.4 R&D Investment (Subject to data availability)
1.2.8.5 Product Types Specification
1.2.8.6 Business Strategy
1.2.8.7 Recent Developments
1.2.8.8 Management Change
1.2.8.9 S.W.O.T Analysis
1.2.9 Uniper SE
1.2.9.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.9.2 Business Overview
1.2.9.3 Financials (Subject to data availability)
1.2.9.4 R&D Investment (Subject to data availability)
1.2.9.5 Product Types Specification
1.2.9.6 Business Strategy
1.2.9.7 Recent Developments
1.2.9.8 Management Change
1.2.9.9 S.W.O.T Analysis
1.2.10 Air Products and Chemicals
1.2.10.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.10.2 Business Overview
1.2.10.3 Financials (Subject to data availability)
1.2.10.4 R&D Investment (Subject to data availability)
1.2.10.5 Product Types Specification
1.2.10.6 Business Strategy
1.2.10.7 Recent Developments
1.2.10.8 Management Change
1.2.10.9 S.W.O.T Analysis
1.2.11 Toshiba Energy Systems and Solutions Corporation
1.2.11.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.11.2 Business Overview
1.2.11.3 Financials (Subject to data availability)
1.2.11.4 R&D Investment (Subject to data availability)
1.2.11.5 Product Types Specification
1.2.11.6 Business Strategy
1.2.11.7 Recent Developments
1.2.11.8 Management Change
1.2.11.9 S.W.O.T Analysis
1.2.12 Green Hydrogen Systems
1.2.12.1 Company Basic Information, Manufacturing Base, Sales Area, and Competitors
1.2.12.2 Business Overview
1.2.12.3 Financials (Subject to data availability)
1.2.12.4 R&D Investment (Subject to data availability)
1.2.12.5 Product Types Specification
1.2.12.6 Business Strategy
1.2.12.7 Recent Developments
1.2.12.8 Management Change
1.2.12.9 S.W.O.T Analysis
Chapter 2. Global Green Hydrogen Market Analysis
2.1 Global Green Hydrogen Market Analysis
2.2 Global Green Hydrogen Market Analysis by Region
2.3 Global Green Hydrogen Market Analysis by Technology
2.4 Global Green Hydrogen Market Analysis by Application
2.5 Global Green Hydrogen Market Analysis by Source
2.6 Global Green Hydrogen Market Analysis by End-use industry
2.7 Global Green Hydrogen Market Analysis by Key Players
Chapter 3. North America Green Hydrogen Market Analysis
3.1 North America Green Hydrogen Market Analysis
3.2 North America Green Hydrogen Market Analysis by Country
3.3 North America Green Hydrogen Market Analysis by Technology
3.4 North America Green Hydrogen Market Analysis by Application
3.5 North America Green Hydrogen Market Analysis by Source
3.6 North America Green Hydrogen Market Analysis by End-use industry
3.7 North America Green Hydrogen Market Analysis by Key Players
Chapter 4. Europe Green Hydrogen Market Analysis
4.1 Europe Green Hydrogen Market Analysis
4.2 Europe Green Hydrogen Market Analysis by Country
4.3 Europe Green Hydrogen Market Analysis by Technology
4.4 Europe Green Hydrogen Market Analysis by Application
4.5 Europe Green Hydrogen Market Analysis by Source
4.6 Europe Green Hydrogen Market Analysis by End-use industry
4.7 Europe Green Hydrogen Market Analysis by Key Players
Chapter 5. Asia Pacific Green Hydrogen Market Analysis
5.1 Asia Pacific Green Hydrogen Market Analysis
5.2 Asia Pacific Green Hydrogen Market Analysis by Country
5.3 Asia Pacific Green Hydrogen Market Analysis by Technology
5.4 Asia Pacific Green Hydrogen Market Analysis by Application
5.5 Asia Pacific Green Hydrogen Market Analysis by Source
5.6 Asia Pacific Green Hydrogen Market Analysis by End-use industry
5.7 Asia Pacific Green Hydrogen Market Analysis by Key Players
Chapter 6. South America Green Hydrogen Market Analysis
6.1 South America Green Hydrogen Market Analysis
6.2 South America Green Hydrogen Market Analysis by Country
6.3 South America Green Hydrogen Market Analysis by Technology
6.4 South America Green Hydrogen Market Analysis by Application
6.5 South America Green Hydrogen Market Analysis by Source
6.6 South America Green Hydrogen Market Analysis by End-use industry
6.7 South America Green Hydrogen Market Analysis by Key Players
Chapter 7. Middle East Green Hydrogen Market Analysis
7.1 Middle East Green Hydrogen Market Analysis
7.2 Middle East Green Hydrogen Market Analysis by Country
7.3 Middle East Green Hydrogen Market Analysis by Technology
7.4 Middle East Green Hydrogen Market Analysis by Application
7.5 Middle East Green Hydrogen Market Analysis by Source
7.6 Middle East Green Hydrogen Market Analysis by End-use industry
7.7 Middle East Green Hydrogen Market Analysis by Key Players
Chapter 8. Africa Green Hydrogen Market Analysis
8.1 Africa Green Hydrogen Market Analysis
8.2 Africa Green Hydrogen Market Analysis by Country
8.3 Africa Green Hydrogen Market Analysis by Technology
8.4 Africa Green Hydrogen Market Analysis by Application
8.5 Africa Green Hydrogen Market Analysis by Source
8.6 Africa Green Hydrogen Market Analysis by End-use industry
8.7 Africa Green Hydrogen Market Analysis by Key Players
Chapter 9. Technology Analysis
9.1 Proton exchange membrane electrolyzer
9.1.1 Global Proton exchange membrane electrolyzer Market
9.1.2 Global Proton exchange membrane electrolyzer Market by Region
9.2 Alkaline electrolyzer
9.2.1 Global Alkaline electrolyzer Market
9.2.2 Global Alkaline electrolyzer Market by Region
9.3 Solid oxide electrolyzer
9.3.1 Global Solid oxide electrolyzer Market
9.3.2 Global Solid oxide electrolyzer Market by Region
Chapter 10. Application Analysis
10.1 Transport
10.1.1 Global Transport Market
10.1.2 Global Transport Market by Region
10.2 Power
10.2.1 Global Power Market
10.2.2 Global Power Market by Region
10.3 Feedstock
10.3.1 Global Feedstock Market
10.3.2 Global Feedstock Market by Region
10.4 Others
10.4.1 Global Others Market
10.4.2 Global Others Market by Region
Chapter 11. Source Analysis
11.1 Wind
11.1.1 Global Wind Market
11.1.2 Global Wind Market by Region
11.2 Solar
11.2.1 Global Solar Market
11.2.2 Global Solar Market by Region
11.3 Geothermal
11.3.1 Global Geothermal Market
11.3.2 Global Geothermal Market by Region
11.4 Hydropower
11.4.1 Global Hydropower Market
11.4.2 Global Hydropower Market by Region
11.5 Hybrid
11.5.1 Global Hybrid Market
11.5.2 Global Hybrid Market by Region
Chapter 12. End-use industry Analysis
12.1 Food & beverages
12.1.1 Global Food & beverages Market
12.1.2 Global Food & beverages Market by Region
12.2 Medical
12.2.1 Global Medical Market
12.2.2 Global Medical Market by Region
12.3 Chemical
12.3.1 Global Chemical Market
12.3.2 Global Chemical Market by Region
12.4 Petrochemicals
12.4.1 Global Petrochemicals Market
12.4.2 Global Petrochemicals Market by Region
12.5 Glass
12.5.1 Global Glass Market
12.5.2 Global Glass Market by Region
12.6 Others
12.6.1 Global Others Market
12.6.2 Global Others Market by Region
Chapter 13. Qualitative Analysis (Subject to Data Availability)
13.1 Market Drivers
13.2 Market Restraints
13.3 Market Trends
13.4 Market Opportunity
13.5 Technological Road Map (Subject to Data Availability)
13.6 Product Life Cycle (Subject to Data Availability)
13.7 Customer and Buyer Behavior Analysis
13.7.1 Digital Engagement, Customer Experience & Relationship Analysis
13.14.2 AI-Driven Transformation of Industry Value Chain
13.14.3 Evolution of Business Models & Revenue Streams
13.14.4 AI-Driven Product, Service & Innovation Transformation
13.14.5 Customer Behavior, AI Adoption & Future Market Evolution
Chapter 14. TOP 10 Country Analysis
14.1 Country 1
14.2 Country 2
14.3 Country 3
14.4 Country 4
14.5 Country 5
14.6 Country 6
14.7 Country 7
14.8 Country 8
14.9 Country 9
14.10 Country 10
Chapter 15. Research Findings
15.1 Key Takeaways
15.2 Analyst Point of View
15.3 Assumptions and Acronyms
Chapter 16. Research Methodology and Sources
16.1 Primary Data Collection
16.1.1 Steps for Primary Data Collection
16.1.1.1 Identification of KOL
16.1.2 Backward Integration
16.1.3 Forward Integration
16.1.4 How Primary Research Help Us
16.1.5 Modes of Primary Research
16.2 Secondary Research
16.2.1 How Secondary Research Help Us
16.2.2 Sources of Secondary Research
16.3 Data Validation
16.3.1 Data Triangulation
16.4 Data Representation
Athenaeum AI Dashboard
Research Framework · 70:30 Primary:Secondary
Our Proprietary Methodology
Cognitive Market Research and Consulting "The Full Truth" methodology — a rigorous triangulation process that combines primary research, secondary validation, and expert calibration. Implemented by Kalyani Raje and team for the Green Hydrogen Market Analysis Market analysis.
01
Primary Intelligence Gathering
Direct interviews with 50+ industry stakeholders including manufacturers, distributors, end-users, and regulatory bodies across all six regions.
02
Secondary Data Triangulation
Cross-referencing against trade databases, customs records, financial filings, patent databases, and verified industry publications.
03
Expert Validation Protocol
Each data point undergoes validation by minimum two independent domain experts with 15+ years of industry experience.
04
Athenaeum AI Processing
Our proprietary AI platform aggregates, normalizes, and identifies patterns across 10,000+ data points to surface non-obvious insights.
05
Editorial & QA Review
Final review by senior analysts ensures accuracy, coherence, and actionability of all insights and recommendations.
To maintain the integrity of our proprietary methodology and protect our elite expert network, specific source disclosures are reserved for full-access partners. Our research framework is anchored by a 70:30 primary-to-secondary ratio, ensuring your strategy is driven by real-time market intelligence rather than recycled, publicly available, or AI-generated data. Every deliverable includes an exhaustive source directory and grants direct analyst access.
The global green hydrogen market is ready to reform the energy landscape, offering a sustainable answer for battle environmental change while powering economies. With its clean and renewable nature, flexibility, energy storage capabilities, and potential for work creation, green hydrogen has the ability to change different sectors, from industry to transportation.
The Three Pillars of End-to-End Market Research Services
We don't just hand over data. We partner with your team across three integrated service lines — each designed to give you decision-grade intelligence on the Green Hydrogen Market Analysis market.
Service 01
Market Survey
B2BB2C
Structured primary research across both B2B and B2C channels. We design and execute custom surveys targeting manufacturers, distributors, procurement heads, and end-consumers in the green hydrogen market analysis ecosystem — validated by our global panel of 10,000+ industrial respondents.
What's Included
Buyer intent & sentiment analysis
Purchase cycle mapping
Price sensitivity research
Channel preference profiling
Competitive perception study
Most Requested
Service 02
Customized Market Data & Reports
CustomReady Report
Choose from our ready-to-access 8th Edition report or commission a fully customized dataset tailored to your exact strategic questions. Cross-splits, custom geographies, proprietary segmentation — we build the intelligence asset your board actually needs.
What's Included
Ready syndicate report
Custom data scope & segmentation
Excel quantitative models
Board-ready PPT with key findings
Secure cloud portal access
Service 03
Strategic Consultation
With SurveyWith Report
Every survey and every report comes with dedicated analyst consultation. Our senior research team walks your leadership through findings, answers strategic questions in real-time, and helps translate data into your next board presentation or investment thesis.
Tell us the specific segments, regions, or companies you need — and we will tailor the deliverable to your requirements.
Why Trust Us
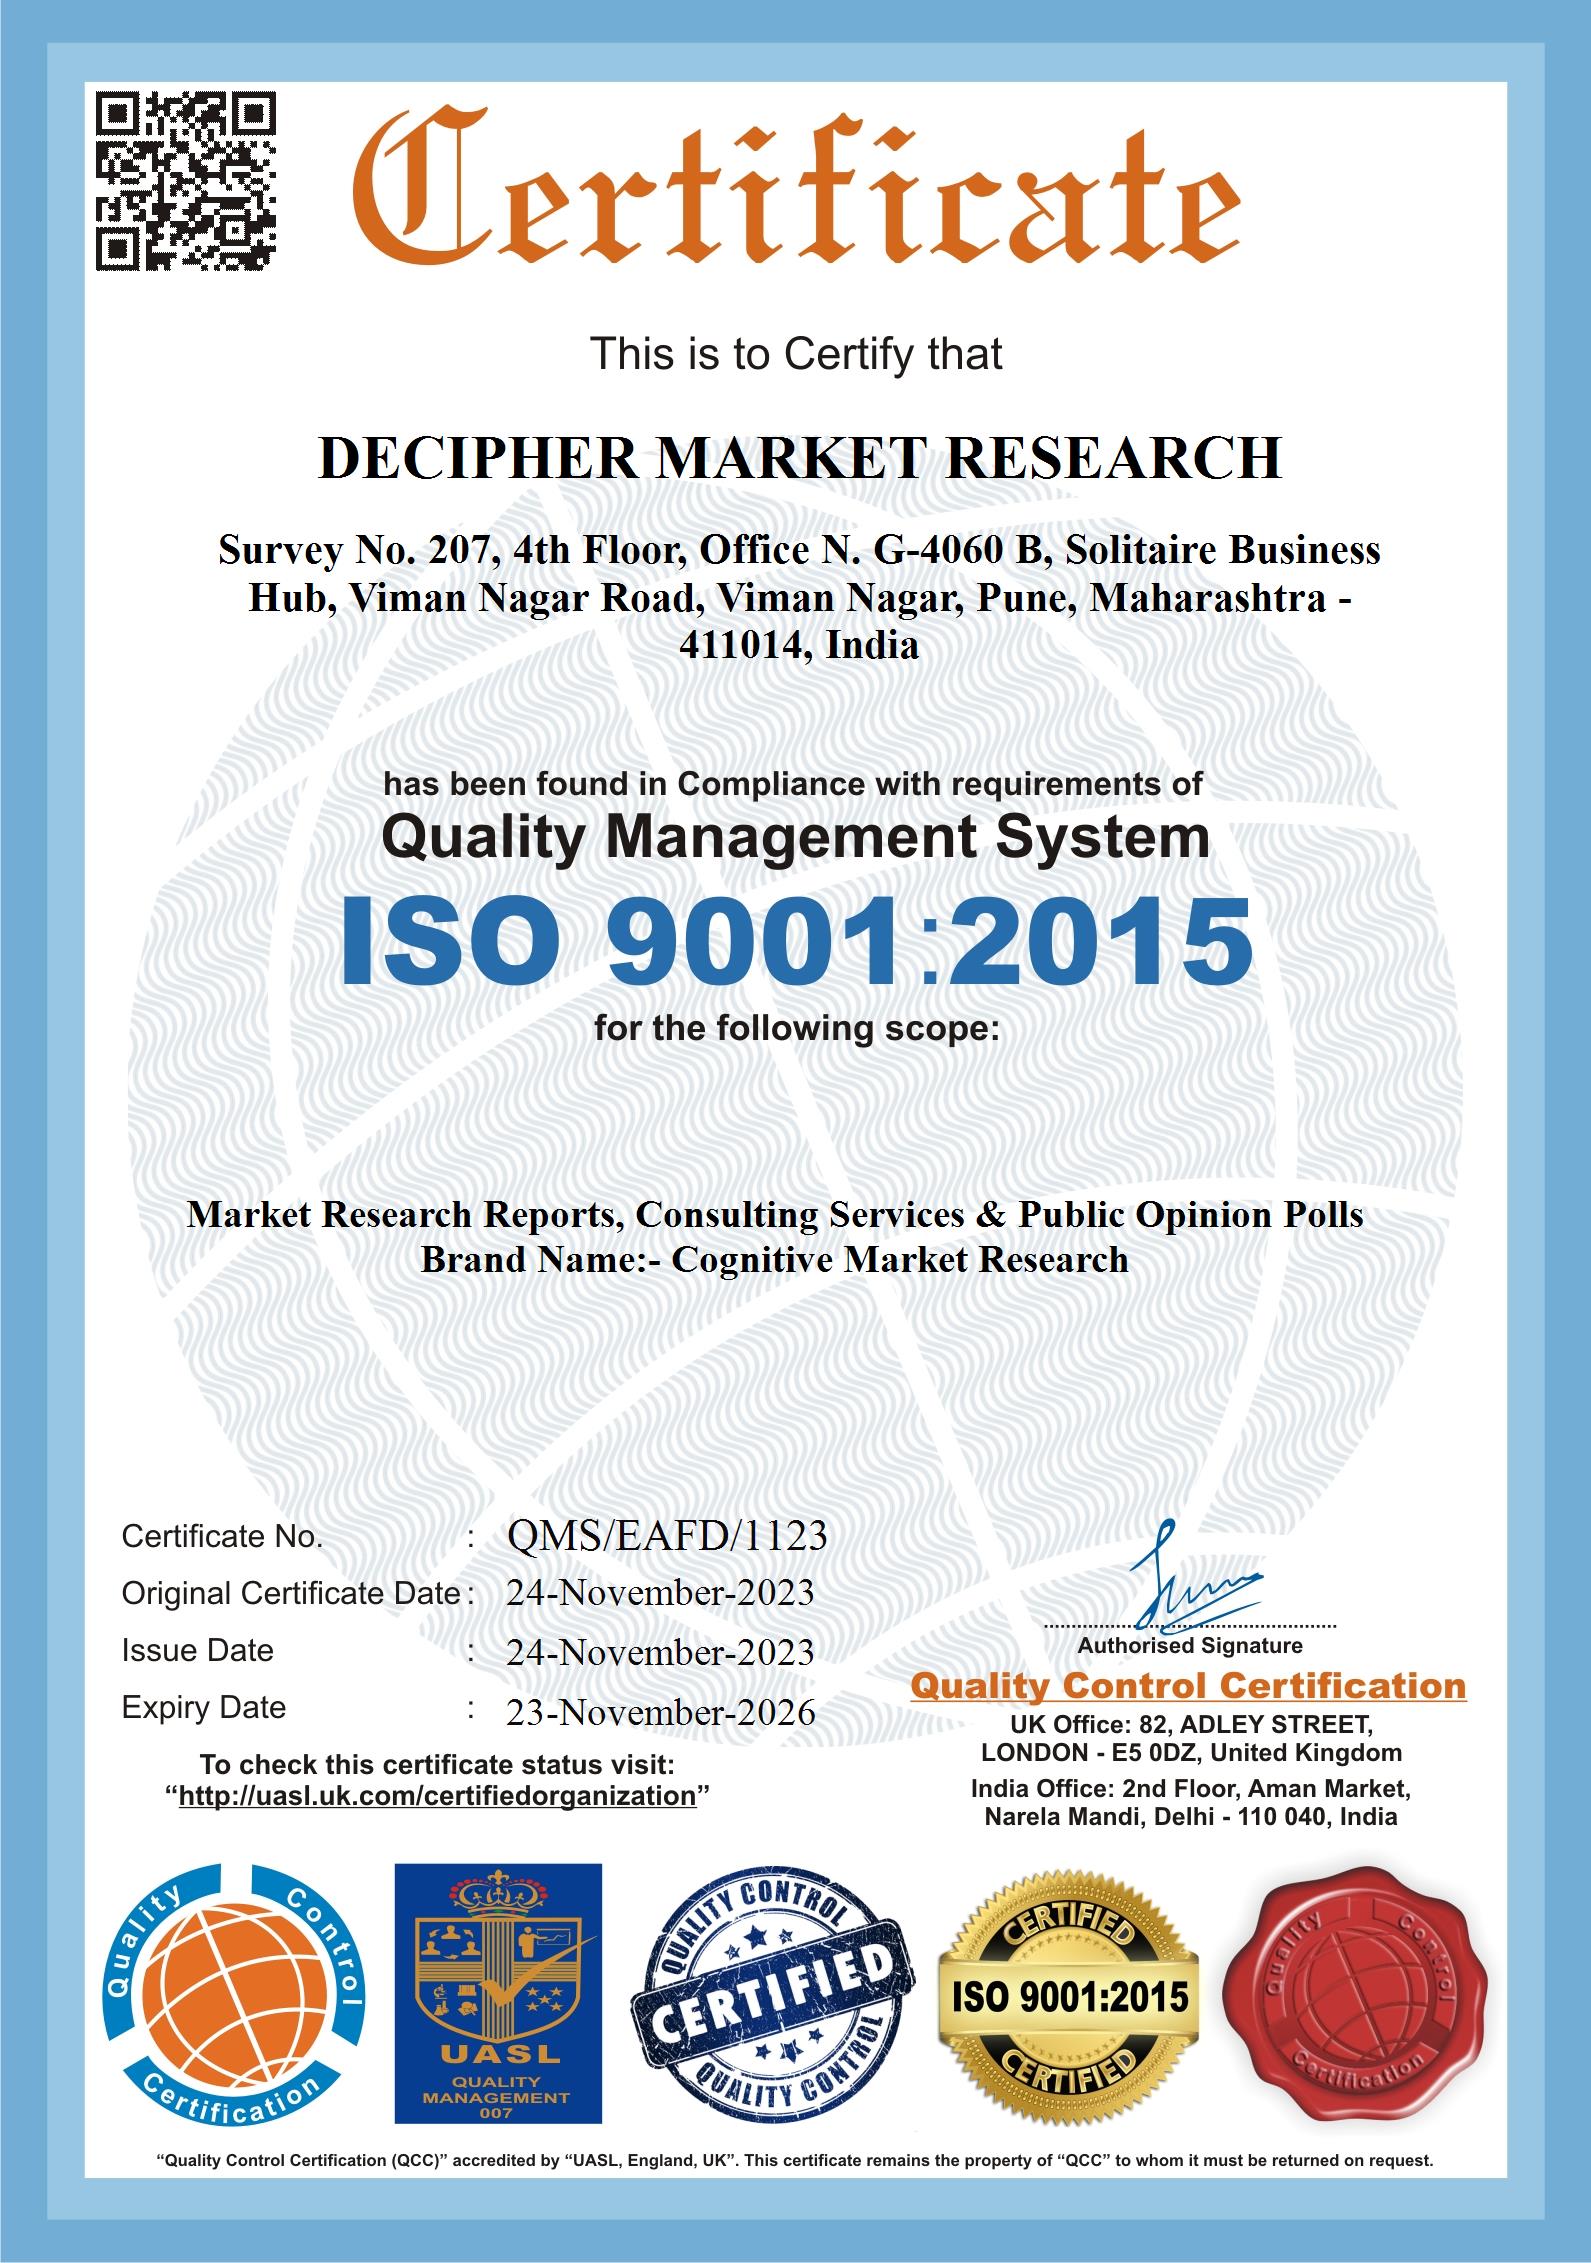
What these certifications mean to usA market figure is only as reliable as the system that produced it. That is why our accreditations cover the whole chain, not just the research step. ESOMAR and MRSI membership binds us to the professional codes that govern how respondents are recruited and how findings may be represented. ISO 20252 governs the research process itself; ISO 9001 and our quality control certification govern how consistently we repeat it. ISO 27001 and ISO 27701, alongside our GDPR, CCPA and DPDP compliance, govern what happens to your brief and your data once it reaches us; because a confidential scope is often more sensitive than the deliverable. ISO 14001, our D-U-N-S registration, Chamber of Commerce membership and DMCA protection speak to how the company itself is run and how its work is safeguarded.Our Clutch and Trustpilot profiles are deliberately listed next to them. They are the only signals on this page we do not issue ourselves, and they are the ones we would check first if we were you.
I can say I was very pleased with everything about the process. Being apart of a startup there are constantly moving parts and key decisions to be anticipa…
The global green hydrogen market is on an aggressive growth path, projected to expand by over 30 times to nearly $100 billion by 2033, driven by a global push for decarbonization.
Asia Pacific, spearheaded by China's industrial strategy and India's national mission, currently constitutes the largest regional market, with a projected 41.9% share in 2025.
Policy is a critical enabler, with frameworks like the U.S. Inflation Reduction Act and Europe's REPowerEU plan creating powerful financial incentives that are accelerating investment and making green hydrogen cost-competitive.
Despite the strong momentum, significant challenges related to the high upfront cost of production, the need for massive infrastructure investment, and water resource management must be overcome to achieve widespread, global adoption.