We value your privacy
We use cookies to improve your experience and analyze traffic. By continuing, you consent to our use of cookies under GDPR, CCPA and other applicable laws. Privacy Policy
Cookie preferences
Choose which categories of cookies you allow. Strictly necessary cookies are always on.
Strictly necessary
Required for core site functionality, security and your session. Always active.
Analytics
Help us understand how visitors use the site (e.g. Google Analytics) so we can improve it.
Marketing
Used to measure campaigns and show you relevant ads on other sites (e.g. LinkedIn, Google Ads).
Cybercrime and Security Market Analysis size 2021 was recorded $122,339 Million whereas by the end of 2026 it will reach $190,820 Million. According to the author, by 2033 Cybercrime and Security market size will become $355,636 Million. Cybercrime and Security market will be growing at a CAGR of 9.638% during 2026 to 2033. Download a free sample with data verified by Aarti Bagekari
Cybercrime and Security Market Analysis from 2022 to 2034 Containing Market Size, Share along with its CAGR, Forecast and Trends
Top Countries — Revenue
Billion
Access the full forecast model.
Country-level data · Company profiles · Editable dataset · Analyst consultation included.
Cybercrime and Security Market Analysis — Presence
Geographical Analysis
Click countries to explore
Loading map…
Regional and Country Analysis
Global Cybercrime and Security Market Analysis 2026
Country-level values are locked in this preview.
Request a free sample
to unlock the full breakdown.
Region / Country
2021 (A)
2025 (A)
2033 (P)
CAGR
Global
$ 122.34 Billion
$ 174.6 Billion
$ 355.64 Billion
9.3%
North America
$ 47.37 Billion
$ 65.69 Billion
$ 125.9 Billion
8.472%
United States
$ 35.22 Billion
$ 48.25 Billion
$ 90.22 Billion
8.136%
Canada
$ 8.81 Billion
$ 12.48 Billion
$ 24.8 Billion
8.964%
Mexico
$ 3.34 Billion
$ 4.95 Billion
$ 10.88 Billion
10.334%
Europe
$ 32.91 Billion
$ 46.44 Billion
$ 91.75 Billion
8.884%
United Kingdom
$ 5.49 Billion
$ 7.51 Billion
$ 13.74 Billion
7.839%
France
$ 4.67 Billion
$ 6.46 Billion
$ 11.75 Billion
7.767%
Germany
$ 7.03 Billion
$ 9.74 Billion
$ 18.41 Billion
8.288%
Italy
$ 3.17 Billion
$ 4.48 Billion
$ 8.53 Billion
8.396%
Russia
$ 2.73 Billion
$ 4.09 Billion
$ 8.26 Billion
9.19%
Spain
$ 2.17 Billion
$ 3.24 Billion
$ 7.23 Billion
10.547%
Sweden
$ 1.48 Billion
$ 2.05 Billion
$ 3.95 Billion
8.51%
Denmark
$ 1.55 Billion
$ 2.37 Billion
$ 5.51 Billion
11.118%
Switzerland
$ 1.38 Billion
$ 2.04 Billion
$ 4.5 Billion
10.358%
Luxembourg
$ 0.49 Billion
$ 0.65 Billion
$ 1.19 Billion
7.88%
Rest of Europe
$ 2.75 Billion
$ 3.82 Billion
$ 8.71 Billion
10.84%
Asia Pacific
$ 26.91 Billion
$ 40.51 Billion
$ 92.47 Billion
10.868%
China
$ 9.06 Billion
$ 14.04 Billion
$ 33.26 Billion
11.379%
Japan
$ 5.27 Billion
$ 7.52 Billion
$ 15.51 Billion
9.464%
South Korea
$ 2.43 Billion
$ 3.58 Billion
$ 7.8 Billion
10.227%
India
$ 3.3 Billion
$ 5.21 Billion
$ 13 Billion
12.111%
Australia
$ 2.22 Billion
$ 3.22 Billion
$ 6.99 Billion
10.156%
Singapore
$ 0.75 Billion
$ 1.01 Billion
$ 1.94 Billion
8.478%
Taiwan
$ 0.78 Billion
$ 1.09 Billion
$ 2.31 Billion
9.806%
South East Asia
$ 2.46 Billion
$ 3.74 Billion
$ 8.64 Billion
11.017%
Rest of APAC
xxxx
xxxx
xxxx
xxxx
South America
$ 6.23 Billion
$ 9.06 Billion
$ 19.17 Billion
9.818%
Brazil
$ 2.56 Billion
$ 3.83 Billion
$ 8.5 Billion
10.486%
Argentina
$ 1.14 Billion
$ 1.66 Billion
$ 3.49 Billion
9.743%
Colombia
$ 0.91 Billion
$ 1.33 Billion
$ 2.89 Billion
10.188%
Peru
$ 0.52 Billion
$ 0.73 Billion
$ 1.43 Billion
8.758%
Chile
$ 0.52 Billion
$ 0.73 Billion
$ 1.45 Billion
8.941%
Rest of South America
$ 0.59 Billion
$ 0.79 Billion
$ 1.42 Billion
7.621%
Middle East
$ 5.51 Billion
$ 7.86 Billion
$ 16.72 Billion
9.896%
Saudi Arabia
$ 2.1 Billion
$ 3.02 Billion
$ 6.55 Billion
10.144%
Turkey
$ 1.05 Billion
$ 1.51 Billion
$ 3.29 Billion
10.249%
UAE
$ 0.88 Billion
$ 1.23 Billion
$ 2.5 Billion
9.269%
Egypt
$ 0.79 Billion
$ 1.12 Billion
$ 2.27 Billion
9.304%
Qatar
$ 0.3 Billion
$ 0.45 Billion
$ 1.06 Billion
11.27%
Rest of Middle East
$ 0.4 Billion
$ 0.53 Billion
$ 1.04 Billion
8.842%
Africa
$ 3.41 Billion
$ 5.05 Billion
$ 9.64 Billion
8.425%
East Africa
xxxx
xxxx
xxxx
xxxx
West Africa
xxxx
xxxx
xxxx
xxxx
North Africa
xxxx
xxxx
xxxx
xxxx
South Africa
$ 1.31 Billion
$ 1.9 Billion
$ 3.45 Billion
7.762%
The global cybercrime and security market is experiencing dynamic growth, driven by an increasingly complex and hostile digital landscape. With a valuation of $122.339 billion in 2021, the market is forecast to reach $174.6 billion in 2025 and soar to $355.636 billion by 2033. This consistent growth underscores the critical importance of cybersecurity in the modern economy, as organizations grapple with protecting sensitive data, intellectual property, and critical infrastructure from a wide array of cyber adversaries.
Global Cybercrime and Security Market Drivers
Increasing Sophistication of Cyber Threats: The continuous evolution of cyberattacks, from ransomware and phishing to state-sponsored espionage, necessitates constant upgrades and investments in advanced security solutions to counter these persistent threats.
Widespread Digital Transformation and IoT Adoption: The proliferation of connected devices, cloud services, and remote work has expanded the potential attack surface for enterprises, making comprehensive security strategies essential for mitigating vulnerabilities.
Stringent Regulatory and Compliance Mandates: Governments worldwide are implementing strict data privacy laws like GDPR and CCPA, forcing organizations to adopt robust security measures to protect consumer data and avoid substantial financial penalties.
Global Cybercrime and Security Market Trends
Integration of AI and Machine Learning: There is a growing trend of embedding AI and ML into security platforms for proactive threat detection, automated response, and predictive analysis, moving from a reactive to a preventative security posture.
Surge in Demand for Cloud Security: As businesses migrate their operations to the cloud, the demand for specialized cloud security solutions (Cloud-Native Application Protection Platforms, Cloud Security Posture Management) has skyrocketed.
Adoption of Zero Trust Architecture: The "never trust, always verify" principle of the Zero Trust model is becoming a mainstream strategy, as it provides enhanced security for complex networks by eliminating implicit trust.
Global Cybercrime and Security Market Restraints
High Cost of Advanced Security Solutions: The significant capital investment required for deploying and maintaining state-of-the-art cybersecurity infrastructure can be a major barrier, particularly for small and medium-sized enterprises (SMEs).
Global Shortage of Skilled Cybersecurity Professionals: A persistent talent gap in the cybersecurity workforce makes it difficult for organizations to effectively manage and operate their security systems, leaving them vulnerable.
Complexity of Integrating Disparate Security Tools: Many organizations struggle with "tool sprawl," where managing a multitude of non-integrated security products creates complexity, visibility gaps, and operational inefficiencies.
Market Size: $47,370 Million (2021) -> $65,685 Million (2025) -> $125,895 Million (2033)
CAGR (2021-2033): 8.472%
Country-Specific Insight: North America holds a commanding 37.6% share of the global market in 2025. The United States leads decisively, accounting for approximately 27.6% of the global market size. Canada and Mexico contribute significantly, holding about 7.1% and 2.8% of the global market respectively, driven by increasing digitalization and cross-border data flows.
Regional Dynamics:
Key Drivers
High concentration of tech companies and critical infrastructure, making it a prime target for cyberattacks.
Early and widespread adoption of cloud, IoT, and 5G technologies.
Strong government focus and investment in national cybersecurity initiatives.
Key Trends
Rapid adoption of Zero Trust architecture across both public and private sectors.
Increased focus on supply chain security following high-profile breaches.
Growing demand for managed detection and response (MDR) services.
Key Restraints
Intense competition among a large number of vendors.
The most severe shortage of skilled cybersecurity talent in the world.
Market saturation in certain legacy security segments.
Technology Focus
The region is at the forefront of adopting advanced AI and ML for predictive threat analytics, sophisticated cloud-native security platforms (CNAPP), and extended detection and response (XDR) solutions for unified security visibility and control.
Market Size: $32,909 Million (2021) -> $46,444 Million (2025) -> $91,754 Million (2033)
CAGR (2021-2033): 8.884%
Country-Specific Insight: Europe represents a substantial 26.6% of the global market in 2025. Germany is the largest contributor, holding 5.6% of the global market, followed by the United Kingdom at 4.3%, and France at 3.7%. Other key markets include Italy (2.6%), Russia (2.3%), and Spain (1.9%), all showing strong growth potential.
Regional Dynamics:
Key Drivers
Stringent regulatory environment, led by the General Data Protection Regulation (GDPR), driving compliance spending.
Increasing government initiatives to bolster digital sovereignty and cybersecurity resilience.
High-profile cyberattacks on public services and industrial sectors.
Key Trends
Growing demand for data privacy management and sovereignty solutions.
Focus on operational technology (OT) and industrial control systems (ICS) security.
Rise of sovereign cloud initiatives impacting security vendor choices.
Key Restraints
Fragmented market with diverse national regulations and languages.
Slower adoption of cutting-edge technologies compared to North America.
Data residency requirements can complicate the use of global cloud security platforms.
Technology Focus
The primary technology focus in Europe is on solutions that ensure GDPR compliance, such as data loss prevention (DLP) and encryption. There is also a strong emphasis on OT security for the industrial sector and secure access service edge (SASE) for secure remote work.
Market Size: $26,914 Million (2021) -> $40,507 Million (2025) -> $92,465 Million (2033)
CAGR (2021-2033): 10.868%
Country-Specific Insight: As the fastest-growing region, APAC will account for 23.2% of the global market in 2025. China is the regional leader, making up 8.0% of the global market. Japan and India are also major players, holding 4.3% and 3.0% of the global market respectively, with India exhibiting one of the highest growth rates globally.
Regional Dynamics:
Key Drivers
Rapid digitalization and massive expansion of internet and mobile users.
Government-led smart city and digital economy projects.
A rising number of sophisticated, state-sponsored cyberattacks within the region.
Key Trends
Strong focus on mobile security due to the mobile-first nature of the region.
Increased investment in securing digital payment ecosystems.
Leapfrogging to cloud-native and AI-driven security solutions.
Key Restraints
Diverse and varying levels of cybersecurity maturity across countries.
Lack of comprehensive data protection regulations in some nations.
Significant shortage of local cybersecurity expertise and awareness.
Technology Focus
Technology adoption is geared towards mobile security, securing digital payment platforms, and cloud security. As many businesses are born in the cloud, there's a strong uptake of modern, scalable security architectures like SASE and cloud-native solutions.
Market Size: $6,227 Million (2021) -> $9,062 Million (2025) -> $19,169 Million (2033)
CAGR (2021-2033): 9.818%
Country-Specific Insight: South America is an emerging market, comprising 5.2% of the global share in 2025. Brazil is the dominant force, accounting for 2.2% of the total global market. Other notable markets like Argentina (0.95%) and Colombia (0.76%) are also experiencing accelerated growth as digital adoption increases.
Regional Dynamics:
Key Drivers
Growing e-commerce and fintech sectors are driving the need for better security.
Increasing government efforts to digitize public services.
Rising awareness of cyber risks due to an increase in banking trojans and phishing attacks.
Key Trends
Adoption of cloud-based security services, especially among SMEs.
Increased focus on fraud prevention and identity management solutions.
Growth in managed security services to compensate for the skills gap.
Key Restraints
Economic instability and political uncertainty in some countries.
Budget constraints and lower cybersecurity spending compared to mature regions.
General lack of cybersecurity awareness among the general population and smaller businesses.
Technology Focus
The technology focus is on foundational security controls, anti-fraud technologies for the financial sector, and accessible, cost-effective cloud-based security solutions. Managed Security Service Providers (MSSPs) play a crucial role in technology delivery.
Market Size: $5,505 Million (2021) -> $7,857 Million (2025) -> $16,715 Million (2033)
CAGR (2021-2033): 9.896%
Country-Specific Insight: The Middle East accounts for 4.5% of the global market in 2025, with significant investment from GCC countries. Saudi Arabia leads the region, holding 1.7% of the global market, followed by the UAE at 0.7% and Turkey at 0.9%. Nations are heavily investing in cybersecurity to protect critical infrastructure and support economic diversification plans.
Regional Dynamics:
Key Drivers
Large-scale government-led economic diversification projects (e.g., Saudi Vision 2030).
High risk of state-sponsored cyberattacks on critical national infrastructure (oil, gas, finance).
Strong government mandates and regulations for cybersecurity.
Key Trends
Heavy investment in national-level Security Operations Centers (SOCs).
Focus on protecting critical infrastructure and OT environments.
Rapid adoption of smart city technologies, requiring integrated security solutions.
Key Restraints
Dependence on expatriate workforce for cybersecurity expertise.
Data localization requirements impacting vendor selection.
Technology Focus
Technology adoption is heavily concentrated on critical infrastructure protection, OT security, and advanced threat intelligence. There is also significant investment in building sovereign security capabilities and training local talent.
Market Size: $3,413 Million (2021) -> $5,046 Million (2025) -> $9,638 Million (2033)
CAGR (2021-2033): 8.425%
Country-Specific Insight: The African market represents approximately 2.9% of the global cybercrime and security market in 2025. South Africa is the largest market on the continent, holding about 1.1% of the global share, with Nigeria following closely at around 0.9%. The market is growing as internet penetration and digital services expand across the continent.
Regional Dynamics:
Key Drivers
Rapid growth in mobile adoption and digital financial services.
Investment in telecommunications infrastructure.
A growing understanding of cyber threats among governments and large corporations.
Key Trends
High demand for mobile security and security for mobile banking applications.
Government initiatives to establish national cybersecurity frameworks and Computer Emergency Response Teams (CERTs).
Increasing adoption of affordable, cloud-delivered security services.
Key Restraints
Limited infrastructure in many parts of the continent.
Severe shortage of cybersecurity skills and training institutions.
Low levels of cybersecurity spending and awareness outside of major economic hubs.
Technology Focus
The primary focus is on securing mobile platforms, which are the primary means of internet access for a majority of the population. There is also a growing need for endpoint security and basic network security, often delivered through MSSPs.
A = Actual · E = Estimated · P = Projected · 🔒 Locked values require full access. Click headers to sort.
Deployment Type breakdown · Illustrative 2025 shares shown free · Full-period forecast in paid report.
Cloud Cybercrime and Security Market Analysis
XX
Cloud Market Size 2025
XX %
CAGR
Locked · Full data in paid report
On-Premises Cybercrime and Security Market Analysis
XX
On-Premises Market Size 2025
XX %
CAGR
Locked · Full data in paid report
Market size by (Illustrative, 2025)
Share distribution (2025)
Disclaimer: The charts and graphs are for illustrative purposes only and do not represent actual market values. To access accurate quantitative data, please request a paid report or request free sample.
To learn more about market share and segmentation, request the free sample pages.
Competitor Analysis
The Cybercrime and Security Market Analysis industry is highly competitive, driven by constant technological innovation and evolving consumer demands. Our report provides an in-depth analysis of the key market players, detailing their business overview, key strategies, recent developments, and a full SWOT analysis. We also include a breakdown of the revenue each company generates specifically within the Cybercrime and Security Market Analysis market.
This comprehensive intelligence allows you to accurately assess how competitors are performing, benchmark your own position, and build effective, data-driven strategies to accelerate your company's growth across all regions.
Click any bar or cell to request the full company profile
Top Companies (In no particular order)
2022 (A)
2023 (A)
2024 (A)
2025 (A)
DXC Technology Company
•••
•••
•••
•••
Control Risks
•••
•••
•••
•••
Happiest Minds
•••
•••
•••
•••
EY
•••
•••
•••
•••
Mimecast
•••
•••
•••
•••
Lockheed Martin
•••
•••
•••
•••
Sophos
•••
•••
•••
•••
Symantec
•••
•••
•••
•••
Sera-Brynn
•••
•••
•••
•••
Clearwater Compliance
•••
•••
•••
•••
IBM Security
•••
•••
•••
•••
Cisco
•••
•••
•••
•••
Raytheon Cyber
•••
•••
•••
•••
BAE Systems
•••
•••
•••
•••
Digital Defense
•••
•••
•••
•••
Rapid7
•••
•••
•••
•••
We Provide Regional Breakdown of this Companies and Company specific to any Country, Region, Product/ service as well. We cover market share analysis for publicly listed companies as well as privately held companies, subject to data availability.
The global market for cybercrime and security is on a significant upward trajectory, projected to expand from $122.339 billion in 2021 to $355.636 billion by 2033, demonstrating a robust compound annual growth rate (CAGR) of 9.3%. This expansion is fueled by the escalating frequency and sophistication of cyber threats, compelling organizations across all sectors to increase their investment in security infrastructure. The ongoing digital transformation, including the widespread adoption of cloud computing, IoT devices, and remote work models, has exponentially increased the digital attack surface, making robust security measures a critical business necessity rather than an option. Furthermore, stringent data protection regulations worldwide are mandating higher standards of security, driving compliance-related spending. The market is characterized by rapid technological innovation, with AI and machine learning becoming integral to modern defense mechanisms.
Key strategic insights from our comprehensive analysis reveal:
The market's substantial growth at a 9.3% CAGR is primarily driven by the relentless surge in cyberattacks and the global push for digitalization, making cybersecurity a top priority for businesses and governments.
While North America currently commands the largest market share, the Asia Pacific region is poised to be the fastest-growing market, with a remarkable CAGR of 10.868%, fueled by rapid economic growth and increasing internet penetration.
A definitive trend is the industry's pivot towards advanced technologies, including Artificial Intelligence (AI), machine learning for predictive threat analytics, and the adoption of Zero Trust security frameworks to counter sophisticated threats.
Strategic Recommendations for Manufacturers
To capitalize on the market's growth, manufacturers should prioritize several key strategies. Firstly, innovation in AI-powered threat intelligence and automated response systems is crucial to stay ahead of evolving threats. Developing integrated, cloud-native security platforms that offer a unified view and simplified management can address the market's frustration with tool complexity. Secondly, focusing on high-growth emerging markets, particularly in the Asia Pacific region, by offering scalable and cost-effective solutions tailored to local needs presents a significant expansion opportunity. Finally, forming strategic partnerships with managed security service providers (MSSPs) can help manufacturers extend their reach to the SME segment, which often lacks in-house expertise, and can provide a recurring revenue stream.
The current industrial landscape is being reshaped by rapid technological progress. Emerging technologies like Artificial Intelligence (AI), the Internet of Things (IoT), and advanced cloud computing are fueling next-generation applications in areas from autonomous vehicles to smart healthcare. While these innovations create immense opportunities, they also present critical challenges, with cybersecurity standing out as a primary concern for the digital age.
Our Market Dynamics analysis drills down into how these broad technological shifts specifically impact the Cybercrime and Security Market Analysis market. We provide a comprehensive assessment of the unique drivers, restraints, opportunities, and challenges your business faces, offering the clarity needed for effective strategic planning. For a detailed discussion, please connect with our sales team.
Analyst Conclusion
As per Cognitive's Research Analyst, Cybercrime and Security are an essential component in safeguarding digital assets and infrastructure within the modern economy. They play an essential role in protecting sensitive data, intellectual property, and critical infrastructure from a wide array of cyber adversaries, ensuring business continuity and regulatory compliance for organizations across all sectors.
Looking at the Historical Growth The global market expanded from $122,339 million in 2021 to an estimated $190,820.00 million in 2026 due to the escalating frequency and sophistication of cyber threats alongside widespread digital transformation. Regionally, North America grew from $47,370 million in 2021 to $71,250.78 million in 2026, while Europe progressed from $32,909 million to $50,569.59 million over the same period.
Currently in 2026, North America holds a commanding 37.34% of the global market, driven by a high concentration of technology companies, critical infrastructure, and robust government investment in national cybersecurity. The solutions for protecting sensitive data and critical infrastructure remain the primary consumer of Cybercrime and Security. Additionally Asia Pacific is set to be the fastest-growing region, exhibiting the highest CAGR of 10.868%, fueled by rapid digitalization, extensive internet penetration, and ambitious government-led digital economy projects.
The market is witnessing a definitive shift towards the integration of AI and machine learning for proactive threat analytics, driven by the continuous evolution of cyberattacks and the industry's shift towards preventative security postures. Ongoing innovation in AI-powered threat intelligence and automated response systems is also leading, focusing on developing integrated, cloud-native security platforms.
In the future, The global Cybercrime and Security market will reach to $355,636 million by 2033, expanding at a compound annual growth rate of 9.3% from 2021, primarily driven by the relentless surge in cyberattacks, coupled with continued global digitalization and stringent regulatory mandates. Ongoing innovation in cyber defense technologies and the strong trend towards the widespread adoption of Zero Trust security frameworks will also contribute significantly.
Research Associate at Cognitive Market Research and Consulting
Driven by a passion for transforming complex digital and business data into actionable market intelligence, Aarti Bagekari focuses her research expertise on the Services & Software and Internet & Communication sectors. Her professional interests lie in analyzing evolving technology ecosystems, digital business models, software innovation, communication infrastructure, and emerging trends that are reshaping the global digital economy.
By leveraging a combination of primary and secondary research methodologies, Aarti develops comprehensive market perspectives that enable organizations to make informed strategic decisions in highly dynamic and competitive environments. Her work involves engaging with industry experts, technology providers, service operators, and key stakeholders while conducting extensive analysis of market data, industry developments, regulatory landscapes, and competitive dynamics. This balanced research approach allows her to uncover meaningful market patterns and identify opportunities that support long-term business growth.
Aarti possesses strong capabilities in market sizing and forecasting, competitive benchmarking, customer and stakeholder research, technology trend analysis, and strategic market assessment. She regularly evaluates developments across software solutions, cloud computing, digital services, telecommunications, internet platforms, enterprise technologies, and next-generation communication networks. Her ability to synthesize large volumes of information into clear and actionable insights helps organizations better understand market shifts, customer expectations, and emerging business opportunities.
At Cognitive Market Research & Consulting, Aarti contributes to market research reports, custom consulting engagements, and survey-based studies that support technology vendors, service providers, investors, and enterprise decision-makers. Her analytical mindset, attention to detail, and commitment to research excellence enable clients to navigate rapidly evolving digital markets, strengthen competitive positioning, and develop sustainable growth strategies in an increasingly connected world.
Cybercrime and Security Market Analysis market size and growth rate is provided in the report covering 2021-2025 historical and 2025-2033 forecast data.
Major factors including drivers, restraints, opportunities and challenges are analyzed with detailed insights.
Top manufacturers DXC Technology Company, Control Risks, Happiest Minds, EY, Mimecast, Lockheed Martin, Sophos, Symantec, Sera-Brynn, Clearwater Compliance, IBM Security, Cisco, Raytheon Cyber, BAE Systems, Digital Defense, Rapid7 and others are profiled in the report.
Segments include Deployment Type, Organization Size and additional sub-segments.
Regional analysis covers all major markets. The report identifies the dominant region and provides country-level data.
Sample pages can be obtained on demand from the website. 24/7 chat support and direct call services are available.
★ Reviews
Rate this report
Cybercrime and Security Market Analysis — Table of Contents
Disclaimer:
This is just a redacted sample pages of the actual deliverable report and only for representative purposes
Charts/Graphs/Numbers/data are only for Representative purposes and do not depict actual statistics.
The table of Contents differs according to the user License selection. Current Displayed TOC is for the Corporate User License Report Edition. TOC Customization options: Add or Remove section/s Or chapter/s from the report.
Specific Tables, Graphs, Sections, and Chapters can be ordered at a discounted price.
If applicable; On Request Volume Data will also be provided (at an Additional Cost).
Report Scope
Deployment Type
Cloud, On-Premises
Organization Size
SMEs, Large Enterprises
Application
IT & Telecom, Retail, BFSI, Healthcare, Defense/Government, Manufacturing, Energy, Others
13.14.2 AI-Driven Transformation of Industry Value Chain
13.14.3 Evolution of Business Models & Revenue Streams
13.14.4 AI-Driven Product, Service & Innovation Transformation
13.14.5 Customer Behavior, AI Adoption & Future Market Evolution
Chapter 14. TOP 10 Country Analysis
14.1 Country 1
14.2 Country 2
14.3 Country 3
14.4 Country 4
14.5 Country 5
14.6 Country 6
14.7 Country 7
14.8 Country 8
14.9 Country 9
14.10 Country 10
Chapter 15. Research Findings
15.1 Key Takeaways
15.2 Analyst Point of View
15.3 Assumptions and Acronyms
Chapter 16. Research Methodology and Sources
16.1 Primary Data Collection
16.1.1 Steps for Primary Data Collection
16.1.1.1 Identification of KOL
16.1.2 Backward Integration
16.1.3 Forward Integration
16.1.4 How Primary Research Help Us
16.1.5 Modes of Primary Research
16.2 Secondary Research
16.2.1 How Secondary Research Help Us
16.2.2 Sources of Secondary Research
16.3 Data Validation
16.3.1 Data Triangulation
16.4 Data Representation
Athenaeum AI Dashboard
Research Framework · 70:30 Primary:Secondary
Our Proprietary Methodology
Cognitive Market Research and Consulting "The Full Truth" methodology — a rigorous triangulation process that combines primary research, secondary validation, and expert calibration. Implemented by Aarti Bagekari and team for the Cybercrime and Security Market Analysis Market analysis.
01
Primary Intelligence Gathering
Direct interviews with 50+ industry stakeholders including manufacturers, distributors, end-users, and regulatory bodies across all six regions.
02
Secondary Data Triangulation
Cross-referencing against trade databases, customs records, financial filings, patent databases, and verified industry publications.
03
Expert Validation Protocol
Each data point undergoes validation by minimum two independent domain experts with 15+ years of industry experience.
04
Athenaeum AI Processing
Our proprietary AI platform aggregates, normalizes, and identifies patterns across 10,000+ data points to surface non-obvious insights.
05
Editorial & QA Review
Final review by senior analysts ensures accuracy, coherence, and actionability of all insights and recommendations.
To maintain the integrity of our proprietary methodology and protect our elite expert network, specific source disclosures are reserved for full-access partners. Our research framework is anchored by a 70:30 primary-to-secondary ratio, ensuring your strategy is driven by real-time market intelligence rather than recycled, publicly available, or AI-generated data. Every deliverable includes an exhaustive source directory and grants direct analyst access.
Latest News about Cybercrime and Security Market
22 Apr 2024economictimes.indiatimes.com
Exclusive: Apple warns users of
Apple plans to tell consumers in India and 91 other countries that their devices may have been targeted by a "mercenary spyware" operation. These assaults are uncommon and more complex than typical cybercriminal activities or consumer malware. Apple has acknowledged that the customer was targeted by a mercenary malware assault that attempted to remotely hack their iPhone using a specific Apple ID. In October 2023, the business sent identical notices to subscribers across various nations, including India. Apple has not identified the state actor behind these assaults, but it has warned consumers in at least 150 countries since 2021. The corporation forbids disclosing further facts about the potential attackers, as it may allow them change their behaviour to avoid detection in the future.
SEC ramps up hack probe with focus on tech, telecom companies, Bloomberg News says
The US Securities and Exchange Commission (SEC) looked into how the SolarWinds cyberattack in 2020 was handled, which exposed the company's network management software, Orion, and permitted access to thousands of businesses and government locations. The SEC has demanded internal communications from affected organizations regarding the effect of the hack, as well as an investigation of organizational security holes. The SEC previously charged the software business and its senior information security officer with misleading investors by concealing cybersecurity flaws during the huge breach. The SEC has not yet replied to Reuters' request for comment.
The Three Pillars of End-to-End Market Research Services
We don't just hand over data. We partner with your team across three integrated service lines — each designed to give you decision-grade intelligence on the Cybercrime and Security Market Analysis market.
Service 01
Market Survey
B2BB2C
Structured primary research across both B2B and B2C channels. We design and execute custom surveys targeting manufacturers, distributors, procurement heads, and end-consumers in the cybercrime and security market analysis ecosystem — validated by our global panel of 10,000+ industrial respondents.
What's Included
Buyer intent & sentiment analysis
Purchase cycle mapping
Price sensitivity research
Channel preference profiling
Competitive perception study
Most Requested
Service 02
Customized Market Data & Reports
CustomReady Report
Choose from our ready-to-access 8th Edition report or commission a fully customized dataset tailored to your exact strategic questions. Cross-splits, custom geographies, proprietary segmentation — we build the intelligence asset your board actually needs.
What's Included
Ready syndicate report
Custom data scope & segmentation
Excel quantitative models
Board-ready PPT with key findings
Secure cloud portal access
Service 03
Strategic Consultation
With SurveyWith Report
Every survey and every report comes with dedicated analyst consultation. Our senior research team walks your leadership through findings, answers strategic questions in real-time, and helps translate data into your next board presentation or investment thesis.
Tell us the specific segments, regions, or companies you need — and we will tailor the deliverable to your requirements.
Why Trust Us
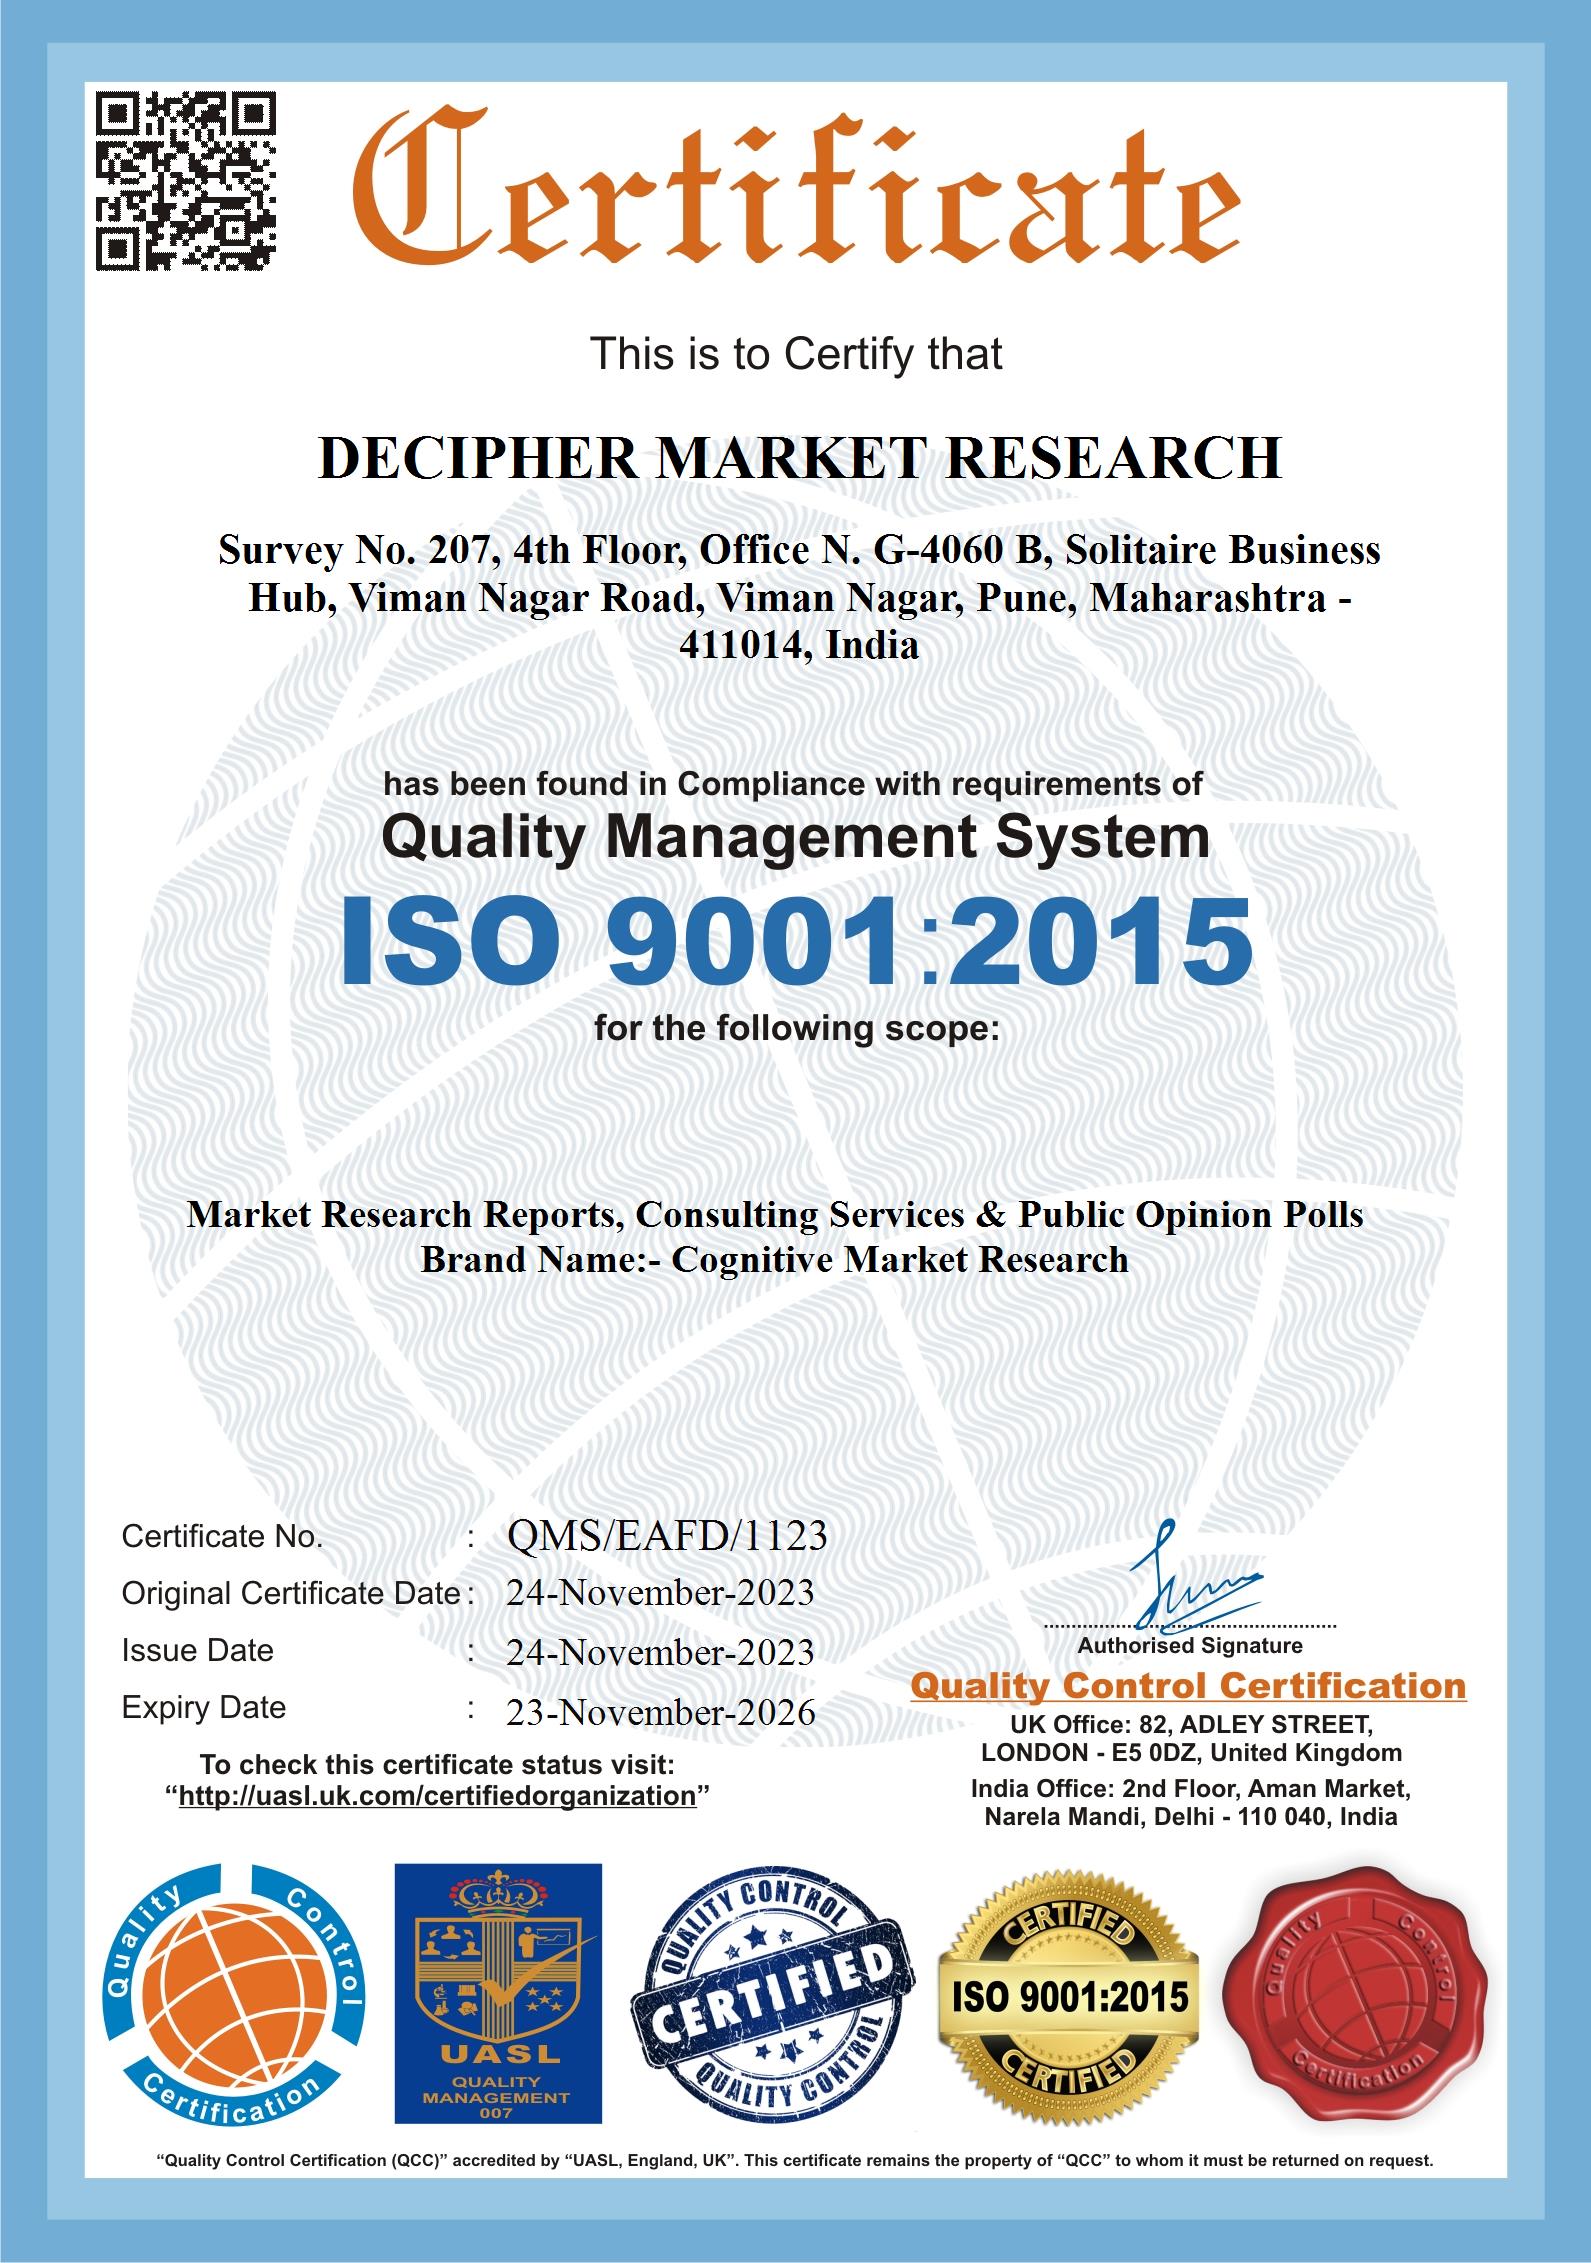
What these certifications mean to usA market figure is only as reliable as the system that produced it. That is why our accreditations cover the whole chain, not just the research step. ESOMAR and MRSI membership binds us to the professional codes that govern how respondents are recruited and how findings may be represented. ISO 20252 governs the research process itself; ISO 9001 and our quality control certification govern how consistently we repeat it. ISO 27001 and ISO 27701, alongside our GDPR, CCPA and DPDP compliance, govern what happens to your brief and your data once it reaches us; because a confidential scope is often more sensitive than the deliverable. ISO 14001, our D-U-N-S registration, Chamber of Commerce membership and DMCA protection speak to how the company itself is run and how its work is safeguarded.Our Clutch and Trustpilot profiles are deliberately listed next to them. They are the only signals on this page we do not issue ourselves, and they are the ones we would check first if we were you.
Working with the CMR was an absolute pleasure. They went above and beyond by providing market sizes for several small markets, where obtaining accurate dat…
The global cybercrime and security market is set for sustained and substantial growth, projected to nearly triple in size from 2021 to 2033, underscoring its enduring relevance in an interconnected world.
While North America currently dominates in market size, the Asia Pacific region is the undeniable growth engine, with its CAGR of 10.868% signaling major opportunities for market expansion and investment.
The technological landscape is being reshaped by the convergence of AI, cloud computing, and Zero Trust principles, compelling vendors to innovate beyond traditional security paradigms to offer integrated, intelligent, and proactive solutions.
Across all regions, the dual forces of increasing threat sophistication and stricter regulatory enforcement act as powerful, non-negotiable drivers that will continue to fuel demand and shape the future of the cybersecurity industry.